How we make this list: we compare pricing pages, product documentation and public user reviews. Ratings come from G2, Capterra or Trustpilot, with the date we checked them.
Key takeaways
- This article is general information only, not financial advice, and no single app shows you the exact score a lender will see, since different lenders use different models.
- Most free apps show VantageScore, while most lenders use FICO, so a free score and a lender score can differ by design, with FICO used by more than 90 percent of top lenders.
- Credit Karma covers two bureaus for free, Experian covers its own bureau with a free FICO score, and myFICO is the direct source for FICO scores across all three bureaus.
- Checking your own score through an app is a soft inquiry and does not lower your score, while paid plans typically cost $13 to $40 per month for three-bureau monitoring plus identity protection.
Quick comparison
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best apps for monitoring credit score
Starting priceFree
Free planYes
Credit Karma is among the most popular free credit monitoring apps, showing VantageScore credit scores from TransUnion and Equifax, but not Experian, with alerts when something changes on those reports, such as a new account, a credit inquiry, or information appearing in a data breach. Its free tier covers everyday monitoring well, with weekly updates in some guides and daily monitoring in others, and its all-in-one tracking suits casual, everyday score tracking across two bureaus. It makes money through targeted recommendations for cards and loans based on your profile.
VantageScore is not the score most lenders use, since FICO scores are used by more than 90 percent of top lenders, so the number a lender sees may differ from the one in the app, and Experian coverage is missing. For free two-bureau tracking with daily monitoring, Credit Karma offers the most popular free starting point here.
What we like- Free all-in-one tracking
- Monitors Equifax and TransUnion daily
- Alerts for new accounts and inquiries
Watch out for- VantageScore 3.0, not FICO
- No Experian coverage
- Free apps funded by financial product offers in the app
Starting priceFree
Free planYes
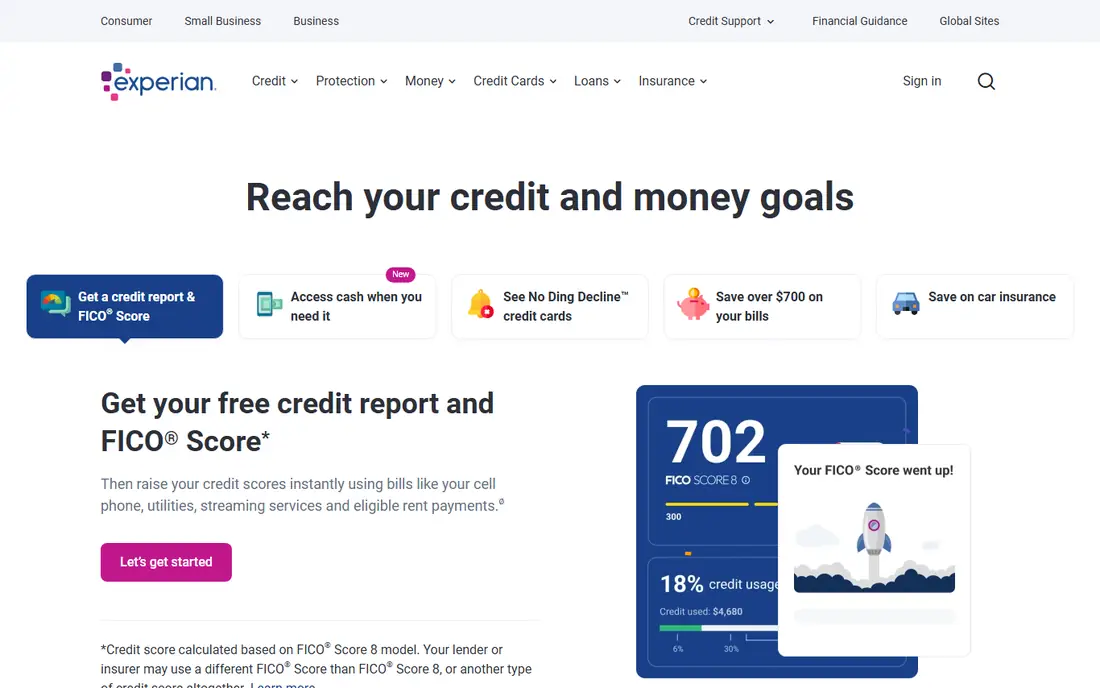
Experian is one of the three major credit bureaus, and its app offers a free FICO Score 8 alongside Experian report monitoring, making it the best free source for a lender-relevant score. Its free Basic plan includes your Experian credit report, a FICO Score, and Experian monitoring, while IdentityWorks Premium costs $24.99 per month after a seven-day free trial and adds daily Experian FICO Scores, three-bureau monitoring, Social Security number alerts, dark web surveillance, up to $1 million in ID theft insurance, and dedicated fraud resolution support. Its Experian Boost feature lets users add utility and rent payments to potentially raise their score.
The free version monitors only Experian, so users need Credit Karma or another app for the other two bureaus, and Premium costs $24.99 per month. For a free FICO score from a direct bureau source, Experian offers the best single-bureau free option here.
What we like- Free FICO Score 8
- Direct bureau monitoring
- Experian Boost for utility and rent payments
Watch out for- Free version monitors only Experian
- Three-bureau monitoring needs Premium at $24.99 per month
Starting priceFree
Free planYes
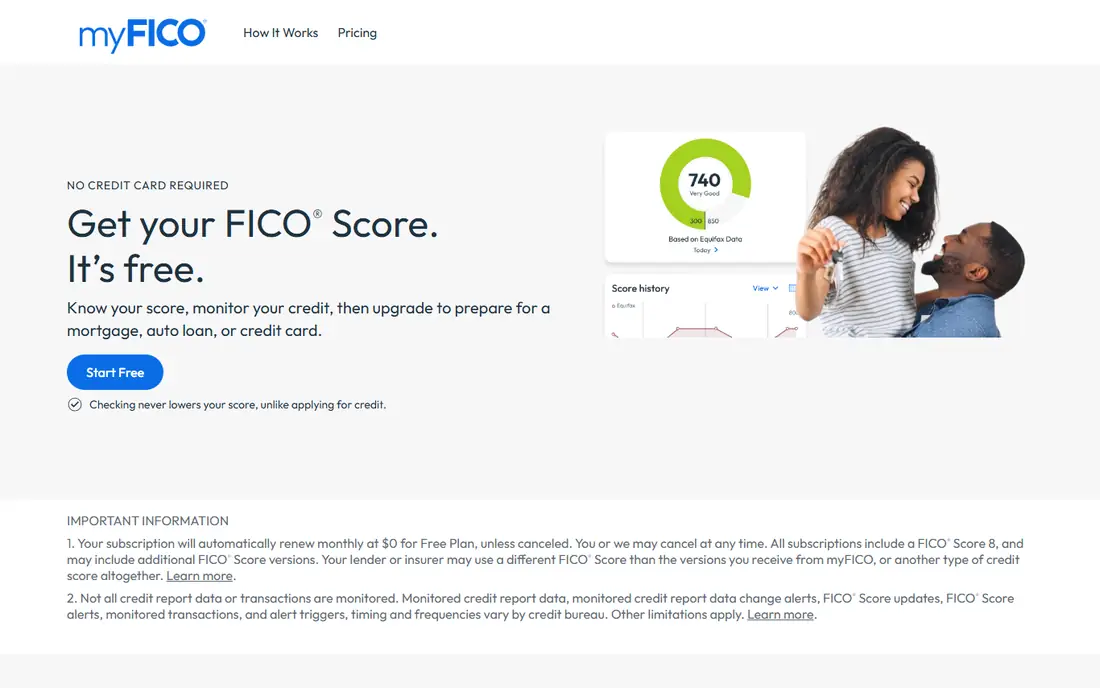
myFICO is the direct source for FICO scores, offering the scores lenders actually use across all three bureaus on paid plans, plus a free plan that gives a FICO Score based on the Experian report, updated monthly in some guides and via Equifax in others. Its paid plans include Advanced at $29.95 per month with all three bureaus updated every three months, and Premier at $39.95 per month with all three bureaus updated monthly, plus a FICO Score 8 Simulator, up to $1 million in ID theft insurance, and 24-hour identity restoration on all plans. It is the best choice for consumers preparing for a major loan application.
Paid plans cost $29.95 to $39.95 per month, the highest in this list, and the free plan covers one bureau with monthly updates. For true FICO scores in the months before a mortgage or auto loan application, myFICO offers the most lender-accurate monitoring here.
What we like- Direct source for FICO scores
- All three bureaus on paid plans
- FICO Score 8 Simulator and ID theft insurance
Watch out for- Advanced at $29.95 and Premier at $39.95 per month
- Free plan covers one bureau with monthly updates
Starting priceFree
Free planYes
Credit Sesame suits users who want free basic monitoring alongside credit-building tools and actionable advice, showing a VantageScore 3.0 from TransUnion on its free tier with guidance on improving credit. Its paid plans run $12.99 to $24.99 per month and add all three bureaus plus deeper monitoring, making it a middle path between free two-bureau tracking and premium FICO services. Its advice features help users understand which actions, such as paying down balances or disputing errors, most affect their score.
The free tier covers TransUnion only, and its score is VantageScore rather than FICO, so lender scores may differ. For free tracking paired with guidance on building credit, Credit Sesame offers the most advice-focused free app here.
What we like- Free tracking with actionable advice
- VantageScore from TransUnion
- All three bureaus on paid plans
Watch out for- Free tier covers TransUnion only
- Paid plans from $12.99 to $24.99 per month
- VantageScore, not FICO
Starting priceFree
Free planYes
WalletHub suits users who want daily updates and a full credit report for free, with VantageScore tracking and report access that goes beyond a single score number. Its daily update cadence beats weekly-update apps for catching changes early, and its full report access helps users spot errors, unfamiliar accounts, and inquiry patterns that a score alone hides. Its free price makes it a strong complement to Credit Karma for users who want daily monitoring.
Its score is VantageScore rather than FICO, and its free model relies on financial product offers inside the app, like other free apps. For daily free updates with full report access, WalletHub offers the most frequent free monitoring here.
What we like- Daily updates and full credit report
- Free
- VantageScore tracking with report access
Watch out for- VantageScore, not FICO
- Free app funded by product offers
- Bureau coverage varies by feature
Starting priceFree
Free planYes
CreditWise by Capital One suits users who want simple free FICO tracking, offering a free FICO Score 8 from TransUnion with a built-in score simulator, and no Capital One account is needed to use it. Its simulator lets users model how actions like paying down a balance or opening a new card might affect their score, which helps with planning before major applications. Its simplicity appeals to users who want one FICO number without juggling multiple apps.
It covers TransUnion only, and simulator results are estimates, not guarantees, since actual lender scores depend on the specific FICO version and bureau data used. For simple free FICO tracking with a simulator, CreditWise offers the easiest free FICO option here.
What we like- Free FICO Score 8 from TransUnion
- Built-in score simulator
- No Capital One account needed
Watch out for- TransUnion only
- Simulator estimates, not guarantees
- Fewer bureaus than paid plans
#7
Chase Credit Journey
Best for: Free score without a Chase account
Visit chase.com
Starting priceFree
Free planYes
Chase Credit Journey suits users who want a free score without opening a Chase account, monitoring Experian with a simple interface for casual tracking. Its free access removes the barrier of needing a bank relationship, and its Experian coverage complements Credit Karma two-bureau tracking, since together they cover all three bureaus for free. Its simplicity suits users who check their score occasionally rather than daily.
It covers Experian only, and guides differ on whether its score is VantageScore or FICO, so confirm the model in the app, while its feature set is smaller than Credit Karma. For free Experian monitoring without a bank account, Chase Credit Journey offers the most accessible bureau-specific option here.
What we like- Free score without a Chase account
- Monitors Experian
- Simple interface for casual tracking
Watch out for- Experian only
- VantageScore in some guides, FICO in others, confirm model
- Fewer features than Credit Karma
Starting priceFree
Free planYes
TransUnion suits users who want direct bureau monitoring with a credit lock, offering a free single-bureau plan plus paid plans at $29.95 per month for three-bureau coverage. Its credit lock feature lets users lock and release their TransUnion report quickly, which helps prevent unauthorized applications, while its direct bureau source means report data comes straight from TransUnion rather than through a third party. Its free plan covers TransUnion monitoring with alerts for report changes.
The free plan covers TransUnion only, paid plans cost $29.95 per month, and its score is VantageScore rather than FICO. For direct bureau monitoring with a credit lock, TransUnion offers the most control-focused bureau app here.
What we like- Direct bureau monitoring with credit lock
- Free single-bureau plan
- All three bureaus on paid plans
Watch out for- Free plan covers TransUnion only
- Paid plan at $29.95 per month
- VantageScore, not FICO
How we chose
We compared October 2026 credit monitoring guides, checking score type, bureaus covered, price, free tiers, and update frequency. We favored apps with clear free and paid tiers and published pricing, and we flagged where guides differ, such as myFICO free bureau and Chase Credit Journey score model, rather than inventing figures. We did not claim hands-on testing, and this article is general information only, not financial advice, so confirm current terms on each vendor site before subscribing.
The ideal free stack for complete coverage
For complete coverage at zero cost, combine Credit Karma for everyday score monitoring across TransUnion and Equifax, Experian free tier for the third bureau plus a FICO Score 8, and AnnualCreditReport.com every 3 to 4 months to pull full reports and check for errors. Add your bank free FICO score if available as a tie-breaker when apps disagree, since that covers all three bureaus, both scoring models, full report access, and active monitoring with zero dollars spent. Many apps update daily or weekly, but underlying credit report data only updates every 30 to 45 days, so daily score changes often reflect model recalculation rather than new report data.
Free versus paid tiers stated plainly
Free tiers cover basic monitoring for one or two bureaus with VantageScore or a single FICO score, while paid tiers from $12.99 to $39.95 per month add three-bureau monitoring, more frequent updates, identity theft insurance up to $1 million, dark web surveillance, and fraud resolution support. Most people do not need paid plans every month: use one free app for routine tracking and add a paid FICO service only in the months before a mortgage or auto loan application, then cancel. Paid apps typically cost $13 to $40 per month, and monitoring costs $0 to $50 per month across the full market depending on coverage and family plans.
Protecting your score and identity
Checking your own credit through an app never hurts your score, since it is a soft pull, while lender or landlord checks are hard inquiries that can affect it. Monitor for unfamiliar accounts, inquiries you did not authorize, and address changes, since those signal identity theft, and dispute errors through the bureau and AnnualCreditReport.com rather than paying a repair service. Watch for scams: free credit reports that charge $1 and auto-enroll you in $29 monthly monitoring, sites with names almost identical to AnnualCreditReport.com, and unsolicited calls or emails offering to check your score are often phishing attempts.
Frequently asked questions
Does checking my credit score lower it?
No, checking your own credit through an app is a soft inquiry and does not lower your score. Hard inquiries from lenders or landlords can affect your score, but monitoring your own report never does.
Why does my app score differ from my lender score?
Most free apps show VantageScore, while most lenders use FICO, and different lenders use different FICO versions and bureaus, so scores differ by design. No single app shows the exact score a lender will see, so use myFICO or Experian for lender-relevant FICO scores before major applications.
Do I need credit monitoring from all three bureaus?
You do not necessarily need all three, but monitoring Equifax, Experian, and TransUnion gives the most coverage of your credit activity, since some lenders report to only one or two bureaus. The free stack of Credit Karma plus Experian plus AnnualCreditReport.com covers all three at zero cost.
Is paid credit monitoring worth it?
Paid monitoring is worth it if you want more frequent updates, three-bureau monitoring, or identity protection and cybersecurity features, but many free services cover the basics. Use paid plans in the months before a major loan application, then cancel, rather than paying year-round.
How often should I check my credit score?
Check monthly for routine tracking, since underlying report data updates every 30 to 45 days, and check more often before a loan application or after a data breach. Daily updates are useful for catching fraud early, but daily score changes often reflect recalculation rather than new data.
Sources we checked (10)
- https://www.creditkarma.com
- https://www.experian.com
- https://www.myfico.com
- https://www.creditsesame.com
- https://wallethub.com
- https://www.creditwise.com
- https://www.chase.com
- https://www.transunion.com
- https://www.moneylion.com/learn/credit/credit-score/best-credit-score-apps
- https://rankite.com/blog/best-credit-score-apps
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has 5+ years in B2B and SaaS SEO. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.
 Credit Karma
 Experian
 myFICO
 Credit Sesame
 WalletHub
 CreditWise
 TransUnion