How we make this list: we compare pricing pages, product documentation and public user reviews. Ratings come from G2, Capterra or Trustpilot, with the date we checked them.
Key takeaways
- Chime Credit Builder is the simplest free path, using a secured card tied to a checking balance with no annual fee.
- Self suits people who want a structured savings-plus-credit plan, starting at $25 a month.
- Experian Boost is free and can add utility and streaming payments to your Experian file, but it only affects one bureau.
- Kikoff's low $5 entry plan makes it the cheapest paid option for reporting a small credit line.
- No app builds credit overnight; expect several months of on-time payments before a meaningful score change.
Quick comparison
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best apps to build credit fast
Starting priceFree
Free planYes
Chime Credit Builder is a secured credit card that works differently from a typical card: you move money from a Chime checking account to the card, spend up to that balance, and Chime reports payments to all three credit bureaus. There is no annual fee, no interest, and no minimum security deposit beyond what you choose to load, which makes it one of the lowest-risk ways to start a credit file.
The requirements are the limit. You need a Chime checking account with a qualifying direct deposit to open the card, and the card offers no rewards. Spending is capped by the money you moved over, so it cannot fund large purchases. For a first-time builder who already banks with Chime, or is willing to switch, it is the cleanest free path.
What we like- No annual fee and no interest
- Reports to all three bureaus
- Spending limited to your balance
Watch out for- Requires a Chime checking account and qualifying deposit
- No rewards
- Secured model limits spending power
Starting price$25/month
Free planNo
Self combines a credit-builder loan with a savings habit. You choose a monthly payment from $25 upward, Self reports those payments to all three bureaus, and at the end of the plan you receive the money back minus fees and interest. That structure suits people who want forced savings alongside credit building, and who do not need a card.
The trade is flexibility. Your money is locked until the plan ends, there is no card to spend with, and a missed payment still damages the file you are trying to build. Self fits disciplined savers who want a set-and-forget plan. If you need spending power, a secured card like Chime's fits better.
What we like- Builds savings while building credit
- Reports to all three bureaus
- Plans from $25 a month
Watch out for- No card or spending flexibility
- Money is locked until the plan ends
- Late payments still hurt
Starting price$5/month
Free planNo
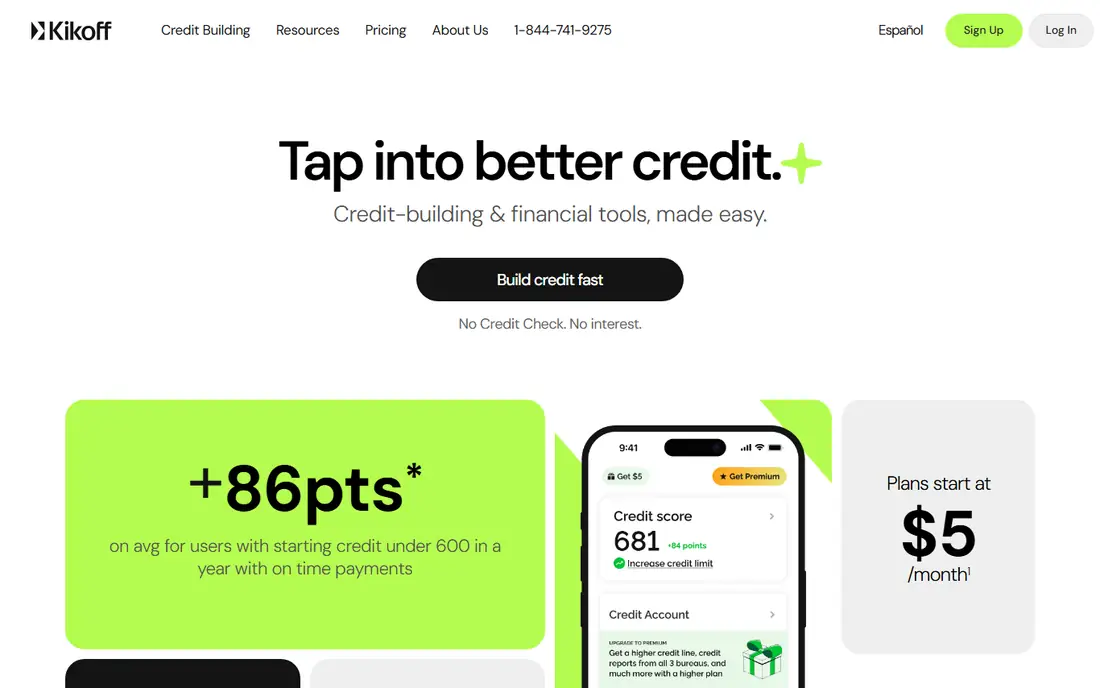
Kikoff offers one of the cheapest paid routes to a reported credit line, with plans starting at $5 a month. The basic plan reports a small revolving line to the major bureaus, and signup is quick and fully online. For someone with no credit file at all, a Kikoff line plus on-time payments can establish reporting history at minimal cost.
The line is small, so its impact on utilization and score is modest compared with a larger secured card, and the basic plan has no card for purchases. Higher tiers add a secured card and larger lines at higher prices. Kikoff suits a first step or a complement to a secured card, rather than a single solution.
What we like- Low $5 entry plan
- Reports to major bureaus
- Simple online signup
Watch out for- Small credit line limits impact
- No card for purchases on the basic plan
- Higher tiers cost more
Starting priceSee website
Free planYes
MoneyLion bundles banking, investing, and credit building in a single app, which suits users who want one financial home rather than several single-purpose apps. Its credit builder products, including loans designed for building history, sit alongside a free account tier, and the app tracks credit scores and offers guidance.
The breadth is also the weakness. Credit builder terms depend on the specific product and membership, so the cost and reporting details need checking on the vendor site before committing, and the app's many features can feel busy. MoneyLion fits users who already want an all-in-one finance app and will use several of its tools.
What we like- Banking, investing, and credit building in one app
- Credit builder loans available
- Free account tier
Watch out for- Credit builder terms sit behind membership details
- Feature breadth can overwhelm
- Fees vary by product
Starting priceFree
Free planYes
Experian Boost is the only genuinely free tool here that can change a score quickly. It connects to your bank account, identifies qualifying utility, phone, and streaming payments, and adds that payment history to your Experian credit file. Users with thin files sometimes see an immediate score increase, and there is no fee at any point.
Two limits matter. Boost only affects Experian, so lenders that pull Equifax or TransUnion will not see the change, and the impact depends on your existing file: users with established history may see little movement. Boost is still worth doing, since it is free and takes minutes, but treat it as a complement to a reporting card or loan, not a replacement.
What we like- Completely free
- Adds utility and streaming payments to your Experian file
- Instant score effect for some users
Watch out for- Only affects Experian, not Equifax or TransUnion
- Needs bank account connection
- Impact varies by profile
Starting priceFree
Free planYes
Grow Credit turns subscriptions into credit history. It issues a virtual Mastercard tied to your existing subscriptions, such as streaming services, and reports those payments to the major bureaus. A free plan covers a small line, with paid memberships raising the line and adding features.
The line is limited to subscriptions, so it cannot build history from general spending, and the score impact depends on the line size and your overall file. Grow Credit suits people who already pay for several subscriptions and want that spending to count, especially as a second reporting line beside a secured card.
What we like- Builds credit from subscriptions you already pay
- Free plan available
- Reports to major bureaus
Watch out for- Line is tied to subscriptions, not general spending
- Higher tiers cost more
- Impact depends on the line size
Starting price$9.99/month
Free planNo
Brigit pairs credit building with cash advances. Its Plus membership, around $9.99 a month, includes a Credit Builder product that reports to the major bureaus, alongside budgeting tools and access to cash advances for eligible users. That combination suits people who want both a credit-building tool and a short-term cash buffer.
The membership is the cost: there is no free credit builder tier, and advance amounts depend on eligibility and banking history. Brigit is not a card, so it does not build revolving history the way a secured card does. It fits users who value the combined package and will use the budgeting and advance features.
What we like- Credit Builder plus cash advances in one membership
- Reports to major bureaus
- Budgeting tools included
Watch out for- Requires a paid Plus membership
- Advances depend on eligibility
- Not a standalone card
Starting priceFree
Free planYes
Current's Build Card follows the secured model: it reports payments to the major bureaus, charges no annual fee, and requires no credit check to apply, with spending limited to the balance in your Current account. That makes it a low-barrier entry for people with no credit file or a damaged one.
As with Chime, the card requires a Current account, spending is capped by your balance, and there are no rewards. Current suits users who already bank with Current or are choosing a new account and want credit building built in from the start, without fees or a hard inquiry.
What we like- No annual fee and no credit check to apply
- Reports to major bureaus
- Tied to a checking balance
Watch out for- Requires a Current account
- Spending limited to your balance
- No rewards program
How we chose
We compared apps and products that report payment history to at least one major credit bureau and are available to US consumers, excluding general credit monitoring that does not build history. Pricing figures come from each vendor's own pricing page and from product listings, checked in October 2026, and where pricing varies by plan or membership we note the starting figure. We weighed reporting breadth, cost, speed of setup, flexibility, and whether the product also serves a second need such as savings or cash flow.
Set realistic expectations
Credit building rewards consistency over months, not weeks. On-time payments, low utilization, and a growing average account age move scores gradually, and no legitimate app can remove accurate negative history or guarantee a specific score increase. Avoid any service that promises instant results or charges large upfront fees for repair.
Stack two reporting lines
One reporting product helps, but two different types, such as a secured card plus a credit-builder loan or subscription line, build a fuller file faster. Keep utilization low, pay on time every month, and let accounts age rather than opening and closing products frequently.
This is not financial advice. Credit products carry fees and risks, and the right choice depends on your income, existing debts, and financial goals. If you are struggling with debt, consider speaking to a nonprofit credit counselor.
Avoiding credit builder traps
Not every product that promises credit building is worth its price. Watch for large upfront fees, monthly charges that exceed the credit line's value, and services that claim they can remove accurate negative items from your file. Legitimate builders report payments and charge modest, clearly stated fees. Anything that guarantees a specific score increase, or asks you to pay hundreds of dollars before any reporting starts, should be treated as a warning sign rather than an opportunity.
Also check which bureaus a product reports to before signing up. A builder that reports only to one bureau helps only lenders that check that bureau, while a card or loan reporting to all three builds a file everywhere. Ask the provider directly, in writing if possible, which bureaus receive reports and how often. Monthly reporting is standard, and anything less frequent slows your progress.
Finally, keep the number of new accounts modest. Opening several builder products at once creates multiple inquiries and lowers your average account age, which can offset the benefit of new positive payment history. One secured card plus one builder loan or subscription line, managed well for a year, usually beats four half-used products opened in the same month.
Frequently asked questions
What is the fastest way to build credit with an app?
A secured card with on-time payments, plus Experian Boost for an immediate Experian effect. Expect meaningful movement over three to six months, not days, and keep utilization low throughout.
Can I build credit for free?
Yes. Chime Credit Builder, Experian Boost, Grow Credit's free plan, and Current's Build Card all report without a monthly fee. Paid options like Self and Kikoff add structure or larger lines, but free tools can establish a file.
Does Experian Boost affect all three bureaus?
No. Experian Boost only adds payment history to your Experian file. Lenders that check Equifax or TransUnion will not see the boost, which is why pairing it with a card that reports to all three bureaus matters.
Will a credit builder loan hurt my score at first?
It can cause a small temporary dip from the new account and inquiry, followed by improvement as on-time payments accumulate. That pattern is normal, and the long-term effect of consistent payments is positive.
How long does it take to build a good credit score?
Most people see a usable score within six months of first reporting, and a good score typically takes a year or more of consistent on-time payments and low utilization. There is no legitimate shortcut to that timeline.
Sources we checked (8)
- https://www.chime.com
- https://www.self.inc
- https://kikoff.com
- https://www.moneylion.com
- https://www.experian.com/boost
- https://growcredit.com
- https://www.hellobrigit.com
- https://current.com
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has 5+ years in B2B and SaaS SEO. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.
 Chime Credit Builder
 Self
 Kikoff
 MoneyLion
 Experian Boost
 Grow Credit
 Brigit
 Current Build Card