How we make this list: we compare pricing pages, product documentation and public user reviews. Ratings come from G2, Capterra or Trustpilot, with the date we checked them.
Key takeaways
- A fiduciary is legally required to act in your best interest, which is a stronger standard than the suitability rule many brokers follow.
- Vanguard, Fidelity and Schwab offer fiduciary advice at large scale, with low-cost funds and broad account options.
- Facet and Empower suit investors who want a dedicated human advisor without a high asset minimum.
- Betterment and Wealthfront suit hands-off investors who prefer automated portfolios with occasional human help.
- Fees are usually a percentage of assets or a flat annual fee, and the exact figure depends on your balance and plan, so confirm it on the firm's pricing page.
A fiduciary investment company is one whose advisors are legally bound to put your interests ahead of their own. That matters because not every person who sells investments works to that standard. Brokers working under a suitability rule only need to recommend something suitable, which leaves room for higher-fee products that pay them more. Fiduciaries must disclose conflicts and recommend what is best for you, even when it pays them less.
The firms below all offer fiduciary advice in some form, but their models differ. Some give you a dedicated human advisor. Others pair automation with access to advisors on demand. Fees, minimums and account types vary, so this guide compares the model first and the price second. This is not financial advice, and the right firm depends on your goals, balance and how much help you want. Prices are marked "See website" where fees depend on balance and plan.
Quick comparison
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best fiduciary investment companies
Starting priceSee website
Free planNo
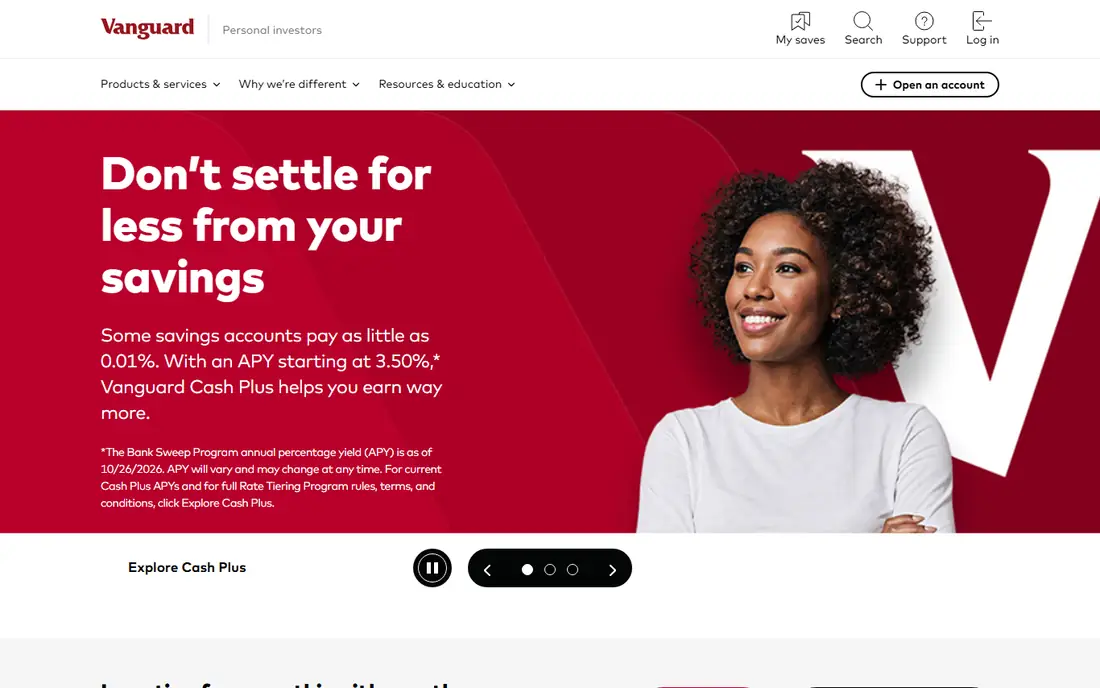
Vanguard is owned by its fund shareholders, which shapes its whole approach. Its Personal Advisor service pairs investors with a human advisor who builds a plan from low-cost index funds and exchange-traded funds, then manages the portfolio and rebalances over time. Because the underlying funds are cheap, the total cost of advice plus funds stays low compared with traditional wealth managers.
The trade-off is access. Dedicated advisor service needs a minimum balance, and the digital experience is plainer than newer competitors. For retirement savers who want fiduciary advice at a low total cost and do not need a fancy app, Vanguard remains the benchmark.
What we like- Advisor services built on low-cost index funds
- Large scale keeps fees down
- Strong retirement planning tools
Watch out for- Human advisor access needs a minimum balance
- Interface feels plain next to newer rivals
#2Fidelity Investments
Best for: All-round investing and advice3.9/5 on
G2 (7 reviews, checked Oct 2026)
Visit fidelity.com
Starting priceSee website
Free planNo
Fidelity covers the whole investing spectrum, from self-directed brokerage to dedicated wealth management. Its advisory services include digital advice for hands-off investors and human advisors for larger accounts, all under a fiduciary standard for advisory accounts. Research tools, retirement planners and a large branch network support investors who want help in person as well as online.
The breadth can overwhelm a beginner. Several advisory tiers with different fees and minimums make comparison work necessary. For investors who want one firm that can grow with them from a first account to full wealth management, Fidelity is the most complete option.
What we like- Wide range from self-directed to full wealth management
- Strong research and planning tools
- Large branch network
Watch out for- Product range can overwhelm beginners
- Advisory fees vary by service tier
Starting priceSee website
Free planNo
Schwab's Intelligent Portfolios offers automated investing with no advisory fee, which makes it one of the cheapest managed options. The trade-off is a cash allocation that can drag returns in strong markets, since part of the portfolio sits in cash earning bank interest. For investors who want a human advisor, Schwab offers planning services at higher tiers, and its branch network gives face-to-face access across the United States.
Banking integration is a plus. Checking, savings and brokerage sit in one login, which simplifies money movement. For cost-conscious investors who want automated management plus the option of in-person advice, Schwab is a strong pick.
What we like- Intelligent Portfolios with no advisory fee
- Branch network for in-person planning
- Strong banking integration
Watch out for- Automated portfolios hold a large cash allocation
- Human advice needs higher balances
Starting priceSee website
Free planNo
Empower, formerly Personal Capital, combines a free financial dashboard with managed advisory services. The dashboard aggregates bank, brokerage and retirement accounts into one view, which helps investors see their whole picture. Managed clients get a dedicated human advisor who builds a plan, manages investments and adjusts for tax and retirement goals.
Advisory service needs a minimum balance, and the percentage fee grows with your portfolio, so very large accounts may find flat-fee firms cheaper. For investors who want a real advisor relationship plus a clear dashboard, Empower is a strong choice.
What we like- Dedicated advisor for managed accounts
- Retirement planning strength
- Dashboard aggregates outside accounts
Watch out for- Advisory minimums apply
- Fees are percentage-based, so costs rise with balance
Starting priceSee website
Free planNo
Facet charges a flat annual fee for planning and investment management, which breaks from the percentage-of-assets model most firms use. Clients get a dedicated advisor team covering investments, retirement, tax planning and career decisions, with regular check-ins. The flat fee means costs do not rise as your portfolio grows, which suits investors building wealth steadily.
For very small balances, a flat fee can cost more than a low percentage fee elsewhere, so the maths depends on your assets. For professionals who want comprehensive planning without watching fees scale with their portfolio, Facet's model is refreshingly clear.
What we like- Flat annual fee rather than percentage of assets
- Dedicated advisor team
- Planning covers career, tax and retirement
Watch out for- Flat fee can be pricey for small balances
- Investment management is part of a planning package
Starting priceSee website
Free planNo
Betterment is the best-known robo-advisor with a fiduciary standard. Portfolios are built from diversified exchange-traded funds, rebalanced automatically, and tax-loss harvesting runs on taxable accounts. Goal-based tools let investors plan separately for retirement, a house deposit or education, with each goal getting its own allocation. A premium tier adds access to human advisors for more complex questions.
Human advice is not included on the basic digital tier, so investors who want regular advisor contact pay more. For hands-off investors who want a well-built automated portfolio and are comfortable with digital-first service, Betterment is the most polished option.
What we like- Automated portfolios with tax-loss harvesting
- Human advisor access on premium tier
- Goal-based planning tools
Watch out for- Human advice needs the higher tier
- Fees rise with premium features
Starting priceSee website
Free planNo
Wealthfront offers automated investing with a clean interface and a high-yield cash account alongside portfolios. Tax-loss harvesting, rebalancing and dividend reinvestment run automatically, and the Path planning tool projects retirement outcomes from your accounts. The service suits investors who want to set a plan and let automation handle it.
There is no dedicated human advisor, which matters when life gets complicated, such as a business sale or an inheritance. For self-directed investors who want automation done well and do not need regular advisor meetings, Wealthfront is a strong, low-friction choice.
What we like- Automated investing with tax-loss harvesting
- High-yield cash account
- Clear, simple interface
Watch out for- No dedicated human advisor
- Planning tools are less deep than Facet or Empower
Starting priceSee website
Free planNo
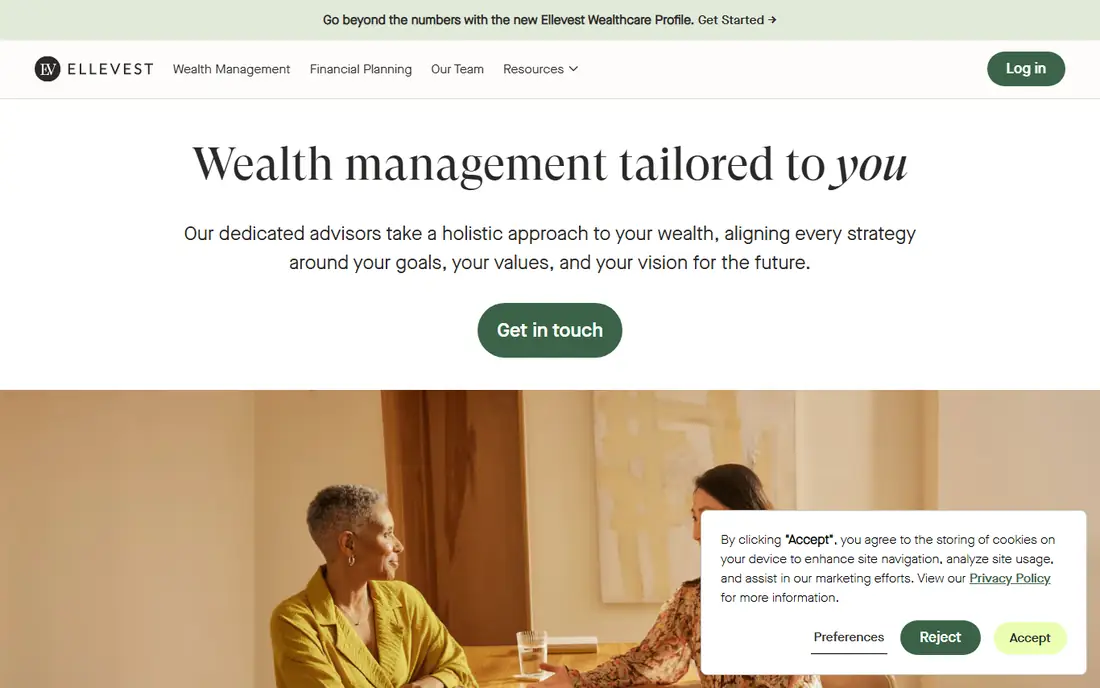
Ellevest designs financial planning around women's financial lives, including longer retirements, career breaks and pay gaps that change saving maths. Membership includes investment management, retirement planning and career coaching such as salary negotiation help. All advice is fiduciary, and the planning tools reflect goals beyond a single retirement number.
The firm is smaller than Vanguard or Fidelity, with fewer account types and a narrower fund menu. For women who want planning that accounts for their specific financial patterns, and coaching alongside investing, Ellevest offers something the giants do not.
What we like- Planning built around women's longer lifespans and pay gaps
- Career and salary coaching
- Fiduciary advice
Watch out for- Smaller firm with fewer account types
- Investment options are narrower than giants
How we chose
We compared firms on their published advice models, fee structures, minimums, account types and public reviews from clients. We favoured firms that clearly state a fiduciary standard for advisory accounts, disclose fees plainly, and offer either dedicated advisors or well-built automation. Prices were marked "See website" because advisory fees depend on balance, service tier and plan. We did not claim hands-on testing, and this guide is not financial advice.
Questions to ask any fiduciary firm
Ask whether the advisor is a fiduciary at all times or only when giving advice on certain accounts, since some firms switch standards by account type. Ask how the advisor is paid, including any commissions or revenue sharing, and whether the firm receives payments from fund providers. Ask what the total cost is, including fund fees, not just the advisory fee.
Also ask about minimums, how often you meet your advisor, and what happens if your advisor leaves. A good firm answers all of these plainly and in writing. If a firm dodges the fiduciary question or bundles fees opaquely, keep looking.
Frequently asked questions
What does fiduciary mean for an investment company?
A fiduciary is legally required to act in your best interest, disclose conflicts of interest, and recommend what is best for you rather than what pays them most. This is a higher standard than the suitability rule that applies to many brokers. Always confirm in writing that your advisor acts as a fiduciary for your account.
Is Vanguard a fiduciary?
Yes, Vanguard's advisory services operate under a fiduciary standard, meaning its advisors must act in clients' best interests. Vanguard's fund-first, low-cost structure supports that model. Confirm the standard applies to the specific service tier you choose, since firms can vary terms by account type.
How much do fiduciary advisors cost?
Costs vary by model. Percentage-of-assets fees are common and scale with your balance, while flat-fee firms charge a set annual amount regardless of balance. Robo-advisors tend to cost less than dedicated human advisors. Check the firm's pricing page and ask for the total cost including underlying fund fees.
Do I need a human advisor or is a robo-advisor enough?
A robo-advisor suits investors with straightforward goals who want automation and low cost. A human advisor helps with complex situations such as business ownership, inheritance, tax planning or retirement drawdown. Some firms offer both, with automation for portfolios and advisors on demand for questions.
What is the difference between a fiduciary and a broker?
A fiduciary must act in your best interest and disclose conflicts. A broker working under a suitability standard must only recommend products that are suitable, which can include higher-fee options that pay the broker more. The legal standard is the key difference, so ask which standard applies to your account.
Can I switch fiduciary firms easily?
Yes, most firms help transfer accounts, and the standard transfer process moves investments without selling them in many cases. Check for account closure fees, tax effects of any sales, and whether your new firm supports the same account types. The transfer usually takes one to two weeks.
Sources we checked (8)
- https://investor.vanguard.com
- https://www.fidelity.com
- https://www.schwab.com
- https://www.empower.com
- https://facet.com
- https://www.betterment.com
- https://www.wealthfront.com
- https://www.ellevest.com
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has 5+ years in B2B and SaaS SEO. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.
 Vanguard
 Charles Schwab
 Empower
 Facet
 Betterment
 Wealthfront
 Ellevest