How we make this list: we compare pricing pages, product documentation and public user reviews. Rankite is independent; if a vendor ever pays for a featured spot, that listing is clearly labeled Partner.
Key takeaways
- Every processor claims to be the cheapest, and the claim is always conditional. The real comparison is your monthly volume, average ticket size, and card mix run through each fee schedule.
- For most small online businesses, Stripe (2.9% + 30 cents) and Braintree (2.89% + 29 cents) are the simple flat-rate picks with no monthly fee.
- Helcim (interchange + 0.50% + 25 cents, no monthly fee) beats flat-rate pricing once volume grows, with automatic discounts as you scale.
- High-volume or global sellers should price Adyen (interchange++ with 0.60% markup) and Stax (subscription + interchange) against the flat-rate options.
Quick comparison
| Tool | Best for | Starting price | Free plan |
|---|
 Stripe | Online-first businesses that want breadth without a monthly fee | 2.9% + $0.30 per successful domestic online card transaction | Yes (no monthly fee; pay-as-you-go) |
 Square | Small retailers and service businesses selling online and in person | 3.3% + $0.30 per online transaction (Free plan) | Yes (Free plan, no monthly fee) |
 PayPal | Sellers who want maximum checkout familiarity | 2.99% + $0.49 per standard US card payment | Yes (no monthly fee to accept payments) |
 Adyen | Mid-market and enterprise merchants with global ambitions | $0.13 + interchange/scheme + 0.60% markup on Visa/Mastercard | No |
 Authorize.net | US small businesses needing a dependable payment gateway | $25/month + 2.9% + $0.30 per transaction (All-in-One) | No |
 Braintree | Growing online businesses wanting PayPal-backed processing | 2.89% + $0.29 per card and digital wallet transaction | No |
 Checkout.com | Large and scaling businesses needing direct card acquiring | See website (quote-based; no public rate card) | No |
 Helcim | US and Canadian SMBs wanting honest interchange-plus pricing | Interchange + 0.50% + $0.25 per transaction (online/keyed, up to $50K/month) | Yes (no monthly fee plan) |
 Stax | Established businesses processing enough volume to beat percentage pricing | $99/month (Growth) + interchange + per-transaction fee, 0% markup | No |
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best software for accepting online payments
Every payment processor claims to be the cheapest. Almost none of them are, for you. The fee that matters is not the headline rate; it is your effective rate after your actual card mix, your average ticket, your refunds and your chargebacks run through the schedule. A flat 2.9% beats interchange-plus for a coffee shop and loses for a furniture store. These nine cover the real options for US businesses taking payments online, with the fee math laid out for each.
#1
Stripe
Best for: Online-first businesses that want breadth without a monthly fee
Visit stripe.com
Starting price2.9% + $0.30 per successful domestic online card transaction
Free planYes (no monthly fee; pay-as-you-go)
Stripe is the default for a reason. Hosted checkout, payment links, invoicing and subscription billing with no monthly fee, cards plus ACH (0.8% capped at $5) plus digital wallets plus 135-plus currencies from one account. Setup takes minutes online with no contract, and it plugs into virtually every e-commerce platform, accounting tool and CRM.
The honest catch is that the fees scale with you. High-volume merchants need a custom enterprise quote to beat the 2.9% base rate, and international cards run 4.4% plus 30 cents. Support is ticket-based for smaller accounts. For an online-first business starting out, the breadth at zero fixed cost is unmatched.
What we like- Developer-friendly APIs and vast integration library
- Cards, ACH, wallets and subscriptions in one platform
- Transparent per-transaction pricing
Watch out for- International cards cost more (4.4% + $0.30)
- Account holds and reserve policies frustrate some small merchants
#2
Square
Best for: Small retailers and service businesses selling online and in person
Visit squareup.com
Starting price3.3% + $0.30 per online transaction (Free plan)
Free planYes (Free plan, no monthly fee)
Square's pitch is one system for every sale. The free plan covers an online store, payment processing, invoices and POS hardware compatibility, which suits cafes, salons and retailers that take money at the counter and on the web. The Plus plan ($49 per month) drops the online rate to 2.9% plus 30 cents.
Do the breakeven math. On the Free plan you pay 3.3% plus 30 cents online; the Plus plan pays for itself once your monthly volume makes the 0.4-point saving exceed $49. Setup is fast with no contracts, and phone and chat support are included. If you only sell online, Stripe or Braintree usually price better.
What we like- Unified online and in-person POS for omnichannel sellers
- Free online store builder included
- Plus plan lowers the online rate
Watch out for- Free-plan online rate is higher than many competitors
- Feature depth trails dedicated e-commerce platforms
#3
PayPal
Best for: Sellers who want maximum checkout familiarity
Visit paypal.com
Starting price2.99% + $0.49 per standard US card payment
Free planYes (no monthly fee to accept payments)
Nobody needs to explain PayPal to your customers. Millions of shoppers have accounts, setup takes minutes with no contract, and the Pay Later option can lift conversion on bigger tickets. For freelancers and small merchants, the familiarity converts.
The fee stack is the catch. Standard card payments run 2.99% plus 49 cents, PayPal Checkout is 3.49% plus 49 cents, and Pay Later costs 4.99% plus 49 cents, so the blended rate climbs fast if buyers choose the expensive options. Fund holds and dispute policies are the most common merchant complaint. Price your actual checkout mix, not the headline rate.
What we like- Huge buyer trust and wallet network
- Quick setup with buttons, invoicing and QR codes
- Pay Later option can lift conversion
Watch out for- Checkout rate is 3.49% + $0.49 and Pay Later is 4.99% + $0.49
- Fund holds and disputes are common complaints
#4
Adyen
Best for: Mid-market and enterprise merchants with global ambitions
Visit adyen.com
Starting price$0.13 + interchange/scheme + 0.60% markup on Visa/Mastercard
Free planNo
Adyen is what serious payments infrastructure looks like. True Interchange++ pricing (a fixed $0.13 plus interchange and scheme fees plus a 0.60% markup), one global platform for online, in-store and marketplace payments, and no setup or monthly fees on standard pricing. At real volume, the transparency beats every flat-rate quote.
It is not for small sellers. The minimum monthly invoice makes it uneconomical at low volume, and onboarding is a sales conversation, not a signup. If you process meaningful volume across markets, get the quote and compare your effective rate. If you are starting out, come back later.
What we like- Interchange++ pricing is transparent and cheap at scale
- One platform for online, in-store and marketplace payments
- No setup or monthly fees on standard pricing
Watch out for- Minimum monthly invoice applies, so small merchants pay more
- Sales-led onboarding, not self-serve
#5
Authorize.net
Best for: US small businesses needing a dependable payment gateway
Visit authorize.net
Starting price$25/month + 2.9% + $0.30 per transaction (All-in-One)
Free planNo
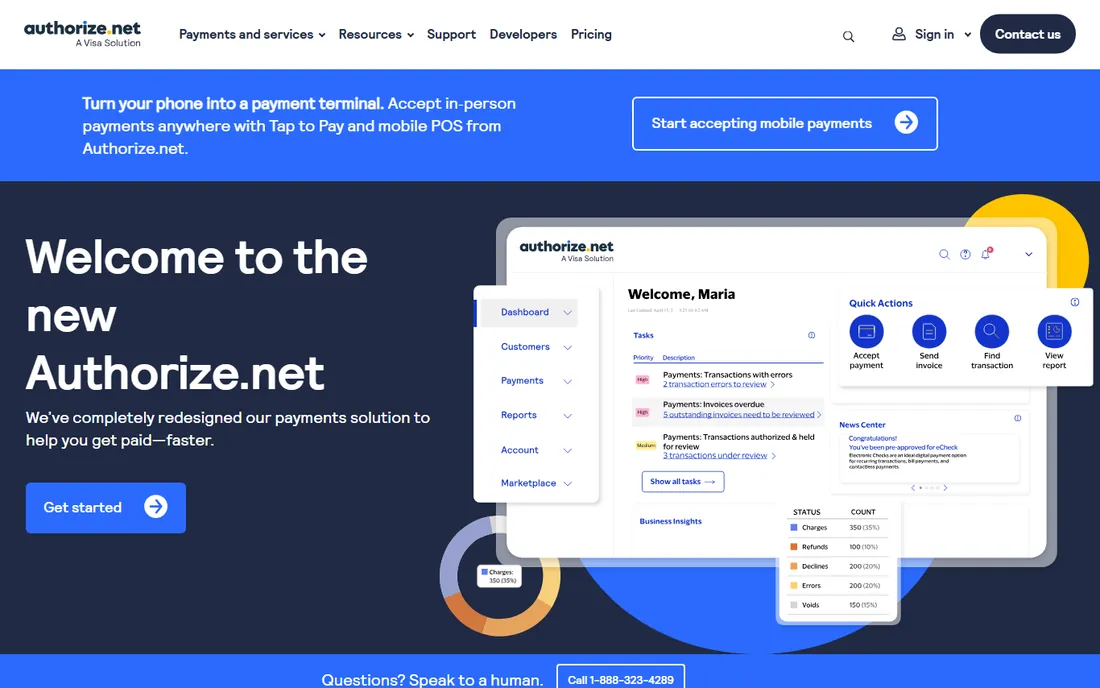
Authorize.net is the veteran. Owned by Visa, compatible with most shopping carts, POS systems and merchant accounts, with recurring billing and a virtual terminal included. For a US business that needs a dependable gateway on an existing merchant account, it just works.
The $25 monthly fee applies even at zero volume, and the Gateway Only option adds 10 cents per transaction plus a daily batch fee. Low-volume merchants will find cheaper options. Setup takes a few days with account approval, and contract terms vary by reseller. Boring in the best way, but price it against Helcim before you commit.
What we like- Long-standing stable gateway brand owned by Visa
- Simple virtual terminal and recurring billing
- Works with most merchant accounts and carts
Watch out for- $25 monthly fee applies regardless of volume
- Interface feels dated next to newer competitors
#6
Braintree
Best for: Growing online businesses wanting PayPal-backed processing
Visit braintree.com
Starting price2.89% + $0.29 per card and digital wallet transaction
Free planNo
Braintree, now marketed as PayPal Enterprise Payments, is the quiet value pick. At 2.89% plus 29 cents it undercuts Stripe's headline rate, with cards, PayPal, Venmo and digital wallets through one integration and ACH at 0.75% capped at $5. The developer SDKs and drop-in UI are genuinely good.
Watch the edges: Venmo runs 3.49% plus 49 cents, chargebacks cost $15, and the PayPal Enterprise packaging has shifted, so confirm which tier applies. For a growing online business that wants PayPal's backing at a slightly better rate than Stripe, the math usually works.
What we like- Flat rate undercuts Stripe and PayPal on cards
- Venmo, PayPal and wallets in one integration
- Strong developer SDKs and drop-in UI
Watch out for- Venmo transactions cost 3.49% + $0.49
- $15 chargeback fee
#7
Checkout.com
Best for: Large and scaling businesses needing direct card acquiring
Visit checkout.com
Starting priceSee website (quote-based; no public rate card)
Free planNo
Checkout.com is infrastructure for companies where payments are a P&L line item. Direct card acquiring across many markets, a high-performance API, and granular control over routing and risk. For a large or scaling online business, the performance and global reach justify the evaluation.
There is no public pricing and no self-serve signup: expect an RFP-style sales process with dedicated onboarding. If you are not processing serious volume across markets, this is the wrong conversation. If you are, get three quotes and make them compete.
What we like- Direct acquiring with strong global coverage
- High-performance API built for enterprise scale
- Flexible pricing tiers for high-volume merchants
Watch out for- No public pricing
- Not self-serve and overkill for small businesses
#8
Helcim
Best for: US and Canadian SMBs wanting honest interchange-plus pricing
Visit helcim.com
Starting priceInterchange + 0.50% + $0.25 per transaction (online/keyed, up to $50K/month)
Free planYes (no monthly fee plan)
Helcim is the honest broker. Interchange-plus pricing with no monthly fee, automatic volume discounts as you grow (online and keyed run interchange + 0.50% + 25 cents up to $50K per month), and ACH at 0.5% plus 25 cents capped at $6. Free invoicing, virtual terminal and online store tools round out the package, with phone, chat and email support reviewers praise.
Keyed and online rates run materially higher than in-person, and the integration library is thinner than the big players. For an SMB doing real online volume that wants to see exactly what the card networks take versus what the processor takes, this is the transparent choice.
What we like- True interchange-plus pricing with zero monthly fee
- Volume discounts kick in automatically
- Free invoicing, virtual terminal and online store tools
Watch out for- Online rate is higher than in-person
- Smaller integration ecosystem than Stripe or Square
#9
Stax
Best for: Established businesses processing enough volume to beat percentage pricing
Visit staxpayments.com
Starting price$99/month (Growth) + interchange + per-transaction fee, 0% markup
Free planNo
Stax bets that subscriptions beat percentages. Growth at $99 per month, Pro at $139, Ultimate at $199, with transactions at interchange plus a flat per-transaction fee and 0% markup. Past a certain volume, the flat subscription plus interchange costs less than any flat-rate processor.
The math cuts both ways: under roughly $10K per month in card volume, the subscription can cost more than a flat-rate processor, so run your own numbers. Note the plan prices come from third-party listings, so confirm on the vendor site before budgeting. For established businesses at real volume, the membership model is worth pricing.
What we like- Subscription pricing with 0% markup beats percentage pricing at volume
- All-in-one dashboard with invoicing and analytics
- Interchange-direct model is transparent
Watch out for- Monthly fee makes it expensive at low volume
- Plan prices from third-party listings, re-check on the vendor site
Flat rate vs. interchange-plus: the math that matters
Payment pricing comes in three shapes. Flat rate (Stripe, Square, PayPal, Braintree) charges one percentage plus a fixed fee per transaction: simple, predictable, and usually the most expensive at scale. Interchange-plus (Adyen, Helcim) passes through the card networks' interchange fees and adds a fixed markup: transparent, and cheaper once volume grows. Subscription (Stax) charges a monthly fee plus interchange with little or no markup: the cheapest at high volume, the most expensive at low volume.
The crossover points are knowable. Run 12 months of your actual processing statements (volume, average ticket, card mix, refunds) through each schedule. The processor that wins at $20K a month often loses at $200K. Never choose on the headline rate alone.
How we chose
We started with the processors US businesses actually evaluate: the flat-rate leaders, the interchange-plus honest brokers, the subscription models, and the enterprise acquirers. For each candidate we opened the vendor's own pricing page, checked the fee schedule against the vendor's merchant fee documentation, and read public reviews on G2, Capterra and practitioner discussion on Reddit. Where a price could not be verified on the vendor's page we wrote "See website" rather than guessing. Fee schedules change, so confirm the current rate before you sign.
How to choose without overpaying on fees
First, know your numbers: monthly volume, average ticket size, and the split between card-present, keyed and online transactions. Without these, every quote is a guess. Second, decide what you value: simplicity (flat rate), transparency (interchange-plus), or lowest cost at scale (subscription or interchange++).
Third, watch the extras that never appear in comparisons. Chargeback fees ($15 at Braintree is typical), monthly minimums, batch fees, PCI compliance fees and fund-hold policies move the real cost. Fourth, check the contract: month-to-month with no cancellation fee beats a cheaper rate with a three-year term. Finally, re-shop annually. Processors rarely lower your rate unprompted, and a competing quote is the fastest discount in the industry.
Frequently asked questions
What is the cheapest way to accept online payments?
It depends on volume. At low volume, Stripe or Braintree at under 2.9% plus ~30 cents with no monthly fee is cheapest. At mid volume, Helcim's interchange-plus with no monthly fee usually wins. At high volume, Stax's subscription model or Adyen's interchange++ beats flat-rate pricing. Run your statements through each schedule.
What is the difference between flat rate and interchange-plus?
Flat rate charges one percentage plus a fixed fee on every transaction, regardless of card type. Interchange-plus passes through the actual interchange fee the card networks charge and adds the processor's fixed markup. Flat rate is simpler; interchange-plus is transparent and usually cheaper at volume.
Do I need a merchant account?
Not necessarily. Stripe, Square, PayPal, Braintree and Helcim are payment facilitators: you get a sub-account with no separate merchant account application. Authorize.net's Gateway Only plan and traditional interchange-plus setups may involve a dedicated merchant account. Facilitators are faster to start; dedicated accounts can price better at scale.
How long does it take to get approved?
Stripe, Square, PayPal and Helcim approve most accounts in minutes to a day with no contract. Authorize.net takes a few days with account approval. Adyen and Checkout.com are sales-led with guided onboarding that takes longer. High-risk categories face more scrutiny everywhere.
Should I offer PayPal at checkout?
If your customers expect it, yes. PayPal's buyer trust can lift conversion, especially for lesser-known stores. But price the mix: PayPal Checkout at 3.49% plus 49 cents and Pay Later at 4.99% plus 49 cents cost more than card processing. Many stores offer PayPal alongside cards and let buyers choose.
Sources we checked (11)
- https://stripe.com/pricing
- https://squareup.com/us/en/pricing
- https://www.paypal.com/us/business/paypal/merchant-fees
- https://www.adyen.com/pricing
- https://www.authorize.net/en-us/pricing.html
- https://www.braintree.com
- https://www.checkout.com/pricing
- https://www.helcim.com/pricing
- https://www.staxpayments.com/pricing
- https://www.g2.com/categories/payment-processing
- https://www.capterra.com/payment-processing-software/
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has spent more than a decade helping SaaS and e-commerce brands grow through search. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.