How we make this list: we compare pricing pages, product documentation and public user reviews. Ratings come from G2, Capterra or Trustpilot, with the date we checked them.
Key takeaways
- AnnualCreditReport.com is the official free source for weekly credit reports from Equifax, Experian, and TransUnion, and every US consumer should start there.
- Experian, Equifax, and TransUnion sell their own reports and monitoring, with FICO scores and identity tools included.
- myFICO suits users who want true FICO scores, since free services often show VantageScore instead.
- Credit Karma and Credit Sesame offer free monitoring and scores, but their scores and recommendations are marketing-driven.
- This article is general information only, not financial advice, and credit decisions should rest on your full financial picture, not one score.
Quick comparison
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best credit report services
Starting priceFree
Free planYes
AnnualCreditReport.com is the official site created under US federal law for free credit reports, and it lets consumers pull weekly reports from Equifax, Experian, and TransUnion at no cost and without a credit card. It is the baseline every consumer should use, since it shows the full report data that lenders see, including accounts, balances, payment history, and inquiries. Checking reports here is the best way to catch errors and fraud early.
The limits are scope. The site gives reports, not scores, and it does not send monitoring alerts, so users must remember to check on their own. Even so, AnnualCreditReport.com suits everyone, since it is free, official, and the first step before paying for any other credit service.
What we like- Official free source
- Weekly reports from all three bureaus
- No subscription or card needed
Watch out for- Reports only, no scores
- No monitoring alerts
- Interface is basic
Starting priceFree
Free planYes
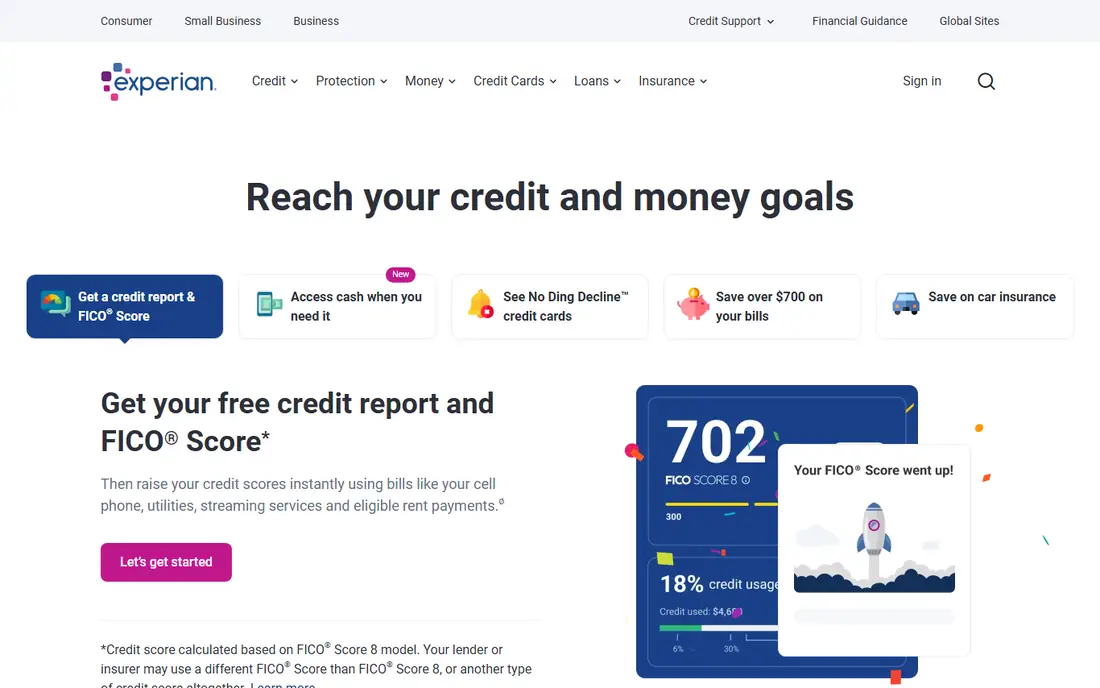
Experian, one of the three major bureaus, offers a free account with an Experian credit report, a FICO score, and basic monitoring, plus paid plans that add daily monitoring, identity protection, and three-bureau reports. Its Boost feature lets users add phone, utility, and streaming payments to their Experian file, which can raise scores for thin-file consumers. The free tier is genuinely useful without a card.
The trade-offs are upsells and scope. Full monitoring and three-bureau coverage need paid plans, upsell prompts are frequent, and the free tier covers only Experian data. Even so, Experian suits users who want a free FICO score and Experian monitoring from the bureau itself.
What we like- Free Experian report and FICO score
- Credit monitoring
- Boost feature for bills
Watch out for- Full monitoring needs a paid plan
- Upsells are frequent
- Only Experian data on free tier
Starting priceFree
Free planYes
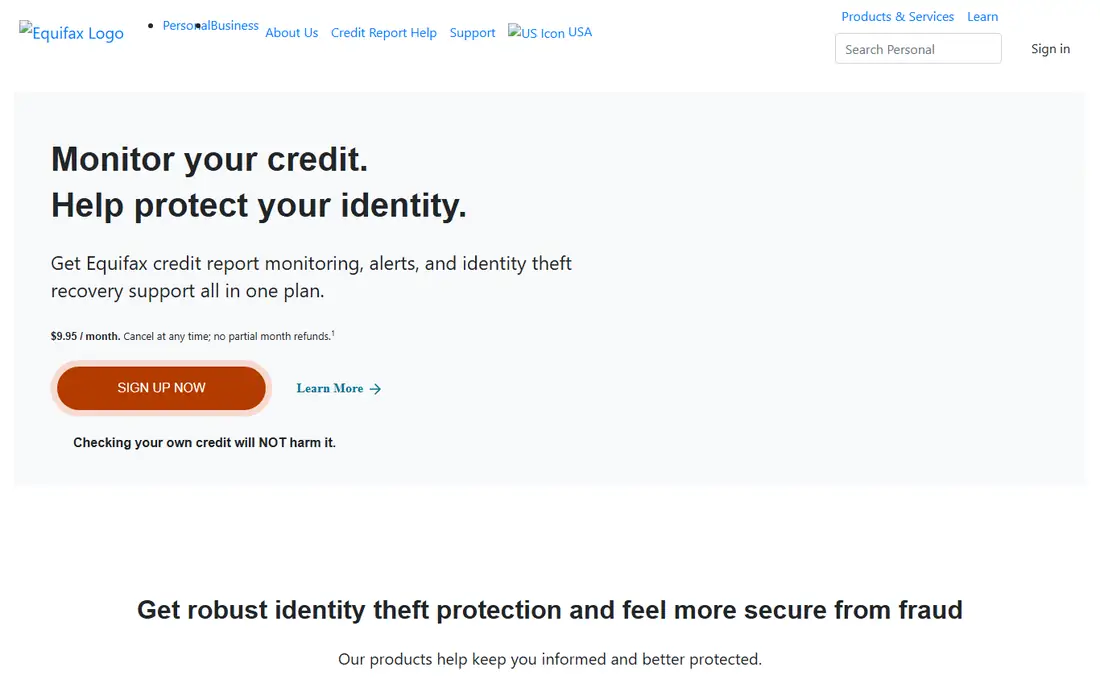
Equifax, another major bureau, offers a free account with an Equifax credit report and score, plus credit lock tools that let users lock and release their Equifax file from an app. Paid plans add three-bureau monitoring, identity protection, and more frequent reports. Locking a file is a strong fraud control, since it blocks new credit in your name until you release it.
The limits are cost and polish. Full three-bureau monitoring needs a paid plan, the interface feels dense, and support quality varies. Even so, Equifax suits users who want direct Equifax data plus a credit lock tool from the bureau itself.
What we like- Free Equifax report and score
- Credit lock tools
- Monitoring on paid plans
Watch out for- Full three-bureau monitoring needs paid plan
- Interface is dense
- Support varies
Starting priceFree
Free planYes
TransUnion, the third major bureau, offers a free account with a TransUnion credit report and score, plus credit lock tools and paid plans for three-bureau monitoring and identity protection. Its lock feature works like Equifax, letting users block new credit until they choose to release it. The free tier gives a useful view of TransUnion data without a card.
The trade-offs are score type and cost. The free score is a VantageScore rather than a FICO score, full monitoring needs a paid plan, and upsells are common. Even so, TransUnion suits users who want direct TransUnion data and a lock tool, especially alongside the other two bureaus.
What we like- Free TransUnion report and score
- Credit lock tools
- Monitoring on paid plans
Watch out for- Full monitoring needs paid plan
- VantageScore on free tier
- Upsells are common
Starting priceSee website
Free planNo
myFICO, from the company behind the FICO score, is the only service that gives consumers the same FICO scores and versions that most lenders use, across all three bureaus. That matters because free services often show VantageScore, which can differ from FICO by dozens of points and mislead borrowers about mortgage or auto loan terms. myFICO also offers monitoring, alerts, and a score simulator for testing how actions affect scores.
The limits are price and free access. Full features need paid plans, there is no free tier, and the cost is higher than free monitoring services. Even so, myFICO suits users preparing for a mortgage, auto loan, or other major credit application who want the exact scores lenders will see.
What we like- True FICO scores lenders use
- All three bureaus
- Score simulator and monitoring
Watch out for- Paid plans only for full features
- No free tier
- Price is higher than free services
Starting priceFree
Free planYes
Credit Karma offers free credit reports, VantageScore scores, and monitoring alerts from Equifax and TransUnion, plus tax filing and financial product tools. Its alerts notify users of new accounts, inquiries, and score changes, which helps catch fraud early, and the service is free because it earns money from product recommendations. Millions of users rely on it for basic monitoring.
The trade-offs are score type and marketing. Scores are VantageScore rather than FICO, ads and credit card offers are heavy, and recommendations are marketing-driven rather than neutral advice. Even so, Credit Karma suits users who want free, ongoing monitoring and alerts without paying for a bureau plan.
What we like- Free reports and scores
- Monitoring alerts
- Tax and financial tools
Watch out for- Scores are VantageScore, not FICO
- Ads and product offers are heavy
- Recommendations are marketing-driven
Starting priceFree
Free planYes
Credit Sesame offers a free TransUnion VantageScore, credit monitoring, and basic identity protection, with paid tiers that add three-bureau monitoring, full identity protection, and more frequent reports. Its interface is simpler than Credit Karma, which suits users who want monitoring without a crowded dashboard. Alerts cover new accounts and score changes.
The limits are score type and depth. The free score is VantageScore, full features need paid plans, and the feature set is smaller than Credit Karma. Even so, Credit Sesame suits users who want simple, free TransUnion monitoring with an easy interface.
What we like- Free TransUnion score and monitoring
- Identity protection on paid tiers
- Simple interface
Watch out for- Score is VantageScore
- Full features need paid plan
- Smaller feature set than Credit Karma
Starting priceSee website
Free planNo
Identity Guard, from Aura, combines identity monitoring with credit reports and scores, using AI to flag risky data exposures, dark web mentions, and identity threats alongside credit changes. It suits users worried about identity theft, since it watches more than credit files, including email addresses, passwords, and personal data in breaches. Family plans cover children and spouses.
The trade-offs are price and score type. Identity Guard is paid only, credit scores shown are VantageScore, and the cost is higher than free monitoring services. Even so, Identity Guard suits users who want identity protection plus credit monitoring in one plan, especially families.
What we like- Identity monitoring plus credit reports
- AI risk alerts
- Family plans available
Watch out for- Paid only
- Credit scores are VantageScore
- Price is higher than free services
How we chose
We compared credit report services on report access, score type, monitoring alerts, identity tools, and price, favoring services with direct bureau data and clear free tiers. We excluded services that charge for reports available free through AnnualCreditReport.com without adding monitoring or scores. Scores in this article are described as FICO or VantageScore where that distinction matters, since the two models can differ sharply.
Buying guide
Start with the free baseline: pull your reports from AnnualCreditReport.com and check every account, balance, payment history entry, and inquiry for errors. Dispute errors with the bureau in writing, since a single wrong late payment can cost points for years and affect loan rates. Next, decide whether you need monitoring: if you are applying for credit soon or have faced fraud, daily alerts help, while occasional report checks suit most users.
Then check score type before you act. Free services usually show VantageScore, while most lenders use FICO, so a VantageScore that looks strong does not guarantee loan terms. If a mortgage or auto loan is near, myFICO gives the scores lenders will see. Finally, freeze your credit files for free at each bureau when you are not applying for credit, since a freeze blocks new accounts in your name more strongly than monitoring alone.
Frequently asked questions
How do I get my credit report for free?
Through AnnualCreditReport.com, the official site, where US consumers can pull weekly reports from Equifax, Experian, and TransUnion at no cost and without a credit card.
What is the difference between FICO and VantageScore?
FICO is the score most lenders use for mortgages, auto loans, and cards, while VantageScore is a competing model shown by many free services today. The two can differ by dozens of points, so always check which score a service shows first.
Should I pay for credit monitoring?
It helps if you are applying for credit soon, have faced fraud, or want daily alerts. For most users, free reports from AnnualCreditReport.com plus free monitoring from Credit Karma or a bureau are enough for everyday needs.
What should I do if I find an error on my report?
Dispute it with the bureau in writing, with evidence, and keep copies of everything you send. Bureaus must investigate, and a corrected error can raise your score once the report is fixed.
Does checking my own credit hurt my score?
No. Checking your own report or score is a soft inquiry and does not affect your score. Only hard inquiries from lenders, when you apply for credit, can lower it slightly, and the effect usually fades within a year.
Sources we checked (0)
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has 5+ years in B2B and SaaS SEO. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.
 AnnualCreditReport.com
 Experian
 Equifax
 TransUnion
 myFICO
 Credit Karma
 Credit Sesame
 Identity Guard