How we make this list: we compare pricing pages, product documentation and public user reviews. Ratings come from G2, Capterra or Trustpilot, with the date we checked them.
Key takeaways
- Vanguard Personal Advisor remains the cheapest human advised option for most investors, at 0.30 percent annually with a $50,000 minimum.
- Fidelity and Merrill suit investors who already bank or broker with those firms, since planning, banking and investing sit together.
- Betterment and Wealthfront suit hands off investors who want automation and tax loss harvesting at 0.25 percent.
- Morgan Stanley and Facet serve opposite ends: full service wealth for large balances, and flat fee planning with no asset minimum.
Quick comparison
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best wealth management companies
Starting price0.30% per year
Free planNo
Vanguard Personal Advisor pairs a dedicated advisor team with low cost index funds, and the fee is the headline advantage. At 0.30 percent annually, a $250,000 portfolio costs about $750 a year, well below most full service firms. Planning covers retirement, tax, estate basics and goal setting, with portfolios built from Vanguard funds and ETFs.
The minimum is $50,000, which excludes smaller savers, and most interaction is remote rather than in a local office. Investors who want a branch advisor or access to alternative investments will find Vanguard narrower than Morgan Stanley or Merrill. For buy and hold investors who want human advice at the lowest sustainable price, Vanguard remains the benchmark.
What we like- Lowest advisory fee among major human advised services
- Low cost fund lineup
- Hybrid digital plus advisor model
Watch out for- $50,000 minimum for Personal Advisor
- Limited local offices
- Higher tier wealth service needs $5 million
Starting price0.50% per year
Free planNo
Fidelity covers the full journey from self directed brokerage to full wealth management inside one account. Brokerage accounts carry no account fee and no commission on US stocks and ETFs, while Fidelity Go offers automated investing from $0, with a 0.35 percent fee above $25,000. Full wealth services add a dedicated advisor and comprehensive planning from $50,000, with fees typically starting near 0.50 percent and rising with complexity.
The breadth can confuse. Coaching, Go, Wealth Services and private wealth tiers overlap, and the right tier depends on balance and needs. Existing Fidelity customers get the most value, since accounts, cash management and planning already sit together. For investors who want one firm for everything, Fidelity is hard to beat.
What we like- No account minimums for brokerage
- Strong research and app
- Coaching and full planning tiers
Watch out for- Advisory fees rise with service level
- $50,000 minimum for full wealth services
Starting priceSee website
Free planNo
Morgan Stanley is the full service end of wealth management. Advisors handle investing, lending, estate and tax coordination, business owner planning and alternative investments such as private equity, real estate and managed futures. Global reach and research depth suit executives, business owners and families with complex, multi entity finances.
Cost and access reflect that scope. Fees are typically near 1 percent annually and minimums are high, with some private programs requiring far more. Smaller investors get little value here and should look at Vanguard, Fidelity or Facet instead. For large, complex wealth where coordination matters more than fee minimization, Morgan Stanley depth justifies the premium.
What we like- Deepest product range, including alternatives
- Global expertise
- Dedicated advisor teams
Watch out for- Highest fees and minimums
- Best suited to large and complex balance sheets
#4
Merrill Wealth Management
Best for: Banking plus investing at Bank of America
Visit ml.com
Starting priceSee website
Free planNo
Merrill, part of Bank of America, suits customers who want banking and investing under one roof. Checking, savings, credit cards and investment accounts link together, and Preferred Rewards tiers add card and banking benefits as combined balances grow. Guided investing offers automated portfolios from $1,000, while full advisor service starts at $20,000 for the advisor led version.
Full service fees run higher than Vanguard or robo advisors, and the strongest banking rewards require large balances. Customers who already bank with Bank of America gain the most, since integration and branch access are real conveniences. Investors focused purely on lowest cost advice will find cheaper options elsewhere.
What we like- Integrated Bank of America banking and rewards
- Advisor access in branches
- Guided investing from lower balances
Watch out for- Advisory fees near 0.90 percent at full service level
- Best rewards need large combined balances
#5
Betterment Premium
Best for: Goal based automated investing with advisor access
Visit betterment.com
Starting price0.25% per year (Digital) / 0.65% per year (Premium)
Free planNo
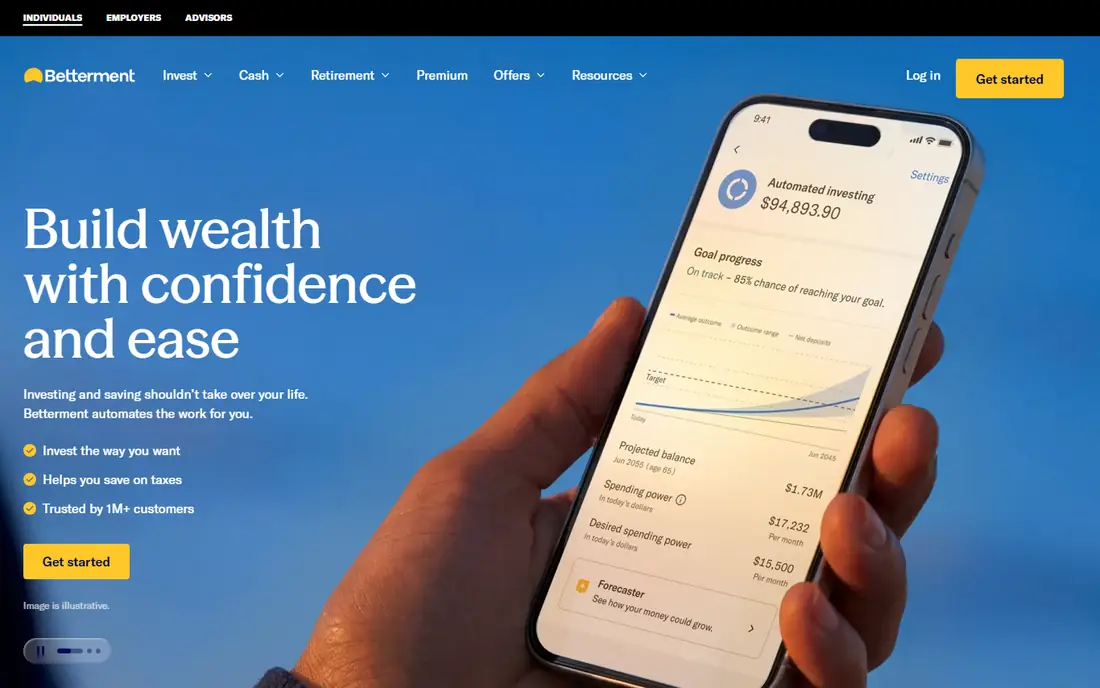
Betterment built its name on automated, goal based investing, and Premium adds human advisors to that engine. Digital portfolios cost 0.25 percent annually, or a flat monthly fee on smaller balances, with automatic rebalancing, dividend reinvestment and tax loss harvesting. Premium, at 0.65 percent from $100,000, adds unlimited access to CFP professionals for planning questions.
The model suits investors who want automation first and advice on demand, rather than a traditional advisor relationship. There are no branches, and alternative investments are limited. For hands off investors who value tax efficiency and a clean goal based interface, Betterment is a strong, low cost choice.
What we like- Low automated fee
- Tax loss harvesting
- Premium adds unlimited advisor access from $100,000
Watch out for- Premium minimum is $100,000
- No branch offices
- Limited alternative investments
Starting price0.25% per year
Free planNo
Wealthfront is the most automation focused firm in this list. The flagship portfolio costs 0.25 percent annually from $500, with daily tax loss harvesting, direct indexing options on higher tiers and a cash account that pays a competitive yield. The interface is clean, and the investing logic is transparent about fees, taxes and risk.
There is no human advisor to call for complex planning, estate or business questions. Investors who need ongoing human guidance should pick Vanguard, Fidelity or Facet instead. For self directed investors who want a well built automated portfolio and strong tax features without advisor meetings, Wealthfront delivers excellent value.
What we like- Strong tax loss harvesting and direct indexing
- Low fee
- Cash account with competitive yield
Watch out for- No human advisor access
- $500 minimum for flagship portfolio
- Limited planning depth
Starting price0.49% per year
Free planNo
Empower combines a free financial dashboard with human advised wealth management. The dashboard links bank, investment, retirement and loan accounts into one net worth view, which helps investors see the full picture before paying for advice. Personal Strategy advisory starts at $100,000, with fees ranging from about 0.49 to 0.89 percent depending on balance and service.
The advisory minimum excludes smaller investors, though the free dashboard remains useful for anyone. Fees sit above Vanguard and robo advisors, but below many full service firms. Investors who already use Empower retirement plans, or who want dashboard plus advisor in one firm, get the most from the combination.
What we like- Free net worth dashboard
- Human advisors from $100,000
- Strong retirement plan heritage
Watch out for- Advisory minimum is $100,000
- Fees rise toward 0.89 percent at lower advisory tiers
Starting priceSee website
Free planNo
Facet breaks the asset based fee model. Instead of charging a percentage of assets, it charges a flat annual fee for a dedicated CFP team, a lifetime financial roadmap and ongoing check ins, with investment management included at no extra fee where chosen. There is no asset minimum, which opens full planning to high income professionals and younger investors who do not yet have large portfolios.
The trade off is scale and history. Facet is smaller and newer than Vanguard, Fidelity or Morgan Stanley, and its model suits planning led clients more than investors who want a large branch network or alternative investments. For buyers who dislike paying more simply because their portfolio grew, the flat fee is a refreshing and often cheaper alternative.
What we like- Flat annual fee, not asset based
- Dedicated CFP team
- No minimum asset requirement
Watch out for- Investment management is optional add on
- Newer and smaller than legacy firms
How we chose
We compared vendor homepages, Form ADV summaries, published fee comparisons and public reviews, focusing on advisory fees, minimums, fiduciary status, planning scope, human advisor access and technology. Every homepage listed was opened and confirmed as belonging to that firm, except Charles Schwab, whose site returned an authorization error and was replaced by Facet. Fees reflect published starting rates and vary by balance and service tier.
This article is general information, not financial advice. Investing involves risk, including possible loss of principal, and advisory fees, taxes and personal circumstances affect outcomes. Consider licensed advice for specific decisions.
Comparing fees honestly
Asset based fees look small as percentages but grow with the portfolio. A 1 percent fee on $1 million is $10,000 a year, every year, while a 0.30 percent fee is $3,000 and a flat fee may be lower still. Add fund expense ratios on top of advisory fees, since a low advisory fee paired with expensive funds can cost more than a higher advisory fee with cheap funds. Ask for the all in cost, including fund fees, trading costs and any platform charges.
Minimums matter as much as fees. A firm with a $100,000 or $250,000 minimum is not an option for a $20,000 saver, no matter how good its service. Flat fee firms and robo advisors fill that gap, while full service firms serve larger, more complex balance sheets. Match the firm to both balance and complexity, not to brand prestige alone.
Questions to ask an advisor
Ask whether the advisor is a fiduciary at all times, how they are paid, what the all in annual cost is at the current balance, and what happens to the fee as the balance grows. Ask who the day to day advisor will be, how often reviews happen, and whether tax, estate and insurance planning are included or referred elsewhere. Clear answers to these questions separate a good fit from an expensive mismatch.
Frequently asked questions
What is the cheapest wealth management option?
Vanguard Personal Advisor is cheapest among major human advised services at 0.30 percent, while Betterment Digital and Wealthfront charge 0.25 percent for automated portfolios. Facet flat fee pricing can be cheaper still for larger balances, depending on the annual fee.
How much money do I need for wealth management?
It varies widely. Facet and robo advisors have no or low minimums, Vanguard needs $50,000, Fidelity wealth services need $50,000, Betterment Premium and Empower need $100,000, and Morgan Stanley needs far more for full service.
Are robo advisors safe?
Robo advisors are registered investment advisers, hold client assets with custodian brokerages, and typically carry SIPC protection for securities. Investing still carries market risk, and SIPC does not protect against market losses.
Should I choose a fiduciary advisor?
Yes, in most cases. A fiduciary is legally required to act in the client best interest, while a broker operating under a suitability standard faces a lower bar. Ask directly whether fiduciary duty applies at all times, not just for certain accounts.
What is the difference between AUM fees and flat fees?
AUM fees charge a percentage of assets managed, so cost rises as the portfolio grows. Flat fees charge a set annual amount regardless of balance, which can be cheaper for larger portfolios and more predictable for planning led clients.
Can I switch wealth managers easily?
Yes, usually by opening an account at the new firm and requesting an in kind transfer of investments. Check for transfer fees, tax consequences of selling positions, and whether proprietary funds must be sold before moving.
Sources we checked (8)
- https://www.vanguard.com/
- https://www.fidelity.com/
- https://www.morganstanley.com/
- https://www.ml.com/
- https://www.betterment.com/
- https://www.wealthfront.com/
- https://www.empower.com/
- https://facet.com/
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has 5+ years in B2B and SaaS SEO. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.
 Vanguard Personal Advisor
 Fidelity Wealth Services
 Morgan Stanley Wealth Management
 Wealthfront
 Empower Wealth
 Facet