How we make this list: we compare pricing pages, product documentation and public user reviews. Ratings come from G2, Capterra or Trustpilot, with the date we checked them.
Key takeaways
- There is no single global Plaid replacement; coverage is regional, so shortlist by the banks your customers actually use.
- MX is the strongest US-first alternative when data quality and enrichment matter more than raw institution count.
- Mastercard Open Finance (Finicity) suits lenders that need structured income and asset verification in the US.
- In Europe, Tink and TrueLayer lead, with TrueLayer stronger when pay-by-bank payments sit beside data access.
- Akoya is the pick when your security review demands API-only access with no credential sharing at all.
Quick comparison
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best Plaid alternatives
#1MX
Best for: US data quality and enrichment4.7/5 on
G2 (14 reviews, checked Oct 2026)
Visit mx.com
Starting priceFree
Free planYes
MX competes with Plaid most directly on the quality of the data that comes back, not just the breadth of connections. Its aggregation pairs with enrichment that cleans, categorizes, and identifies merchants, which matters when a product's value depends on accurate spending insight rather than raw transaction rows. A free developer tier covering a limited set of users at select institutions lets a team prototype before a sales conversation.
The trade is geography and scope. MX is US and Canada centered, and payment initiation is limited compared with European platforms built under PSD2. Teams that need European coverage or pay-by-bank will need a second provider. For US fintechs and banks that rank data accuracy and support responsiveness above all else, MX is the first alternative to test.
What we like- Free developer tier
- Strong transaction categorization and enrichment
- FDX-aligned token access
Watch out for- US and Canada focus
- Enterprise pricing requires sales contact
- Limited payment initiation
#2
Finicity (Mastercard Open Finance)
Best for: US lending and verification
Visit finicity.com
Starting priceSee website
Free planFree trial
Finicity, now part of Mastercard Open Finance, is built for decisions. Its strength is structured verification products: income, assets, and employment signals packaged for mortgage and lending workflows, backed by direct bank relationships and FDX-aligned access. A lender that needs defensible verification data, rather than a generic transaction feed, will find Finicity's product shape closer to the job than a general aggregator.
That enterprise shape is also the limitation. Pricing is agreed through sales, onboarding expects a commercial relationship, and the product is less suited to a small consumer app that wants a quick self-serve integration. If your use case is lending, account verification, or credit decisioning in the US, put Finicity at the top of the shortlist and test its verification outputs against your current decision data.
What we like- Deep US bank relationships
- Structured income and asset products
- FDX support
Watch out for- Enterprise-oriented sales process
- Pricing not published
- Consumer-facing products are not the focus
Starting priceSee website
Free planFree trial
Yodlee is the veteran of this market, with data sources numbering in the tens of thousands across dozens of countries and a long record in wealth management and investment aggregation. Products that need brokerage and retirement accounts alongside checking and cards, or that serve customers across several countries, will find Yodlee's breadth hard to match in a single contract. Credit and enrichment add-ons extend it further for lenders.
The cost of that breadth is an enterprise buying experience and a developer surface that feels older than the newer APIs on this list. Small teams may find the sales process heavy for a first integration. Yodlee fits best where coverage breadth and investment data are requirements, not nice-to-haves, and where an enterprise vendor relationship is already the norm.
What we like- Very broad global data-source coverage
- Long wealth and investment aggregation history
- Analytics add-ons
Watch out for- Enterprise sales process
- Pricing not published
- Developer experience feels older than newer rivals
Starting priceSee website
Free planFree trial
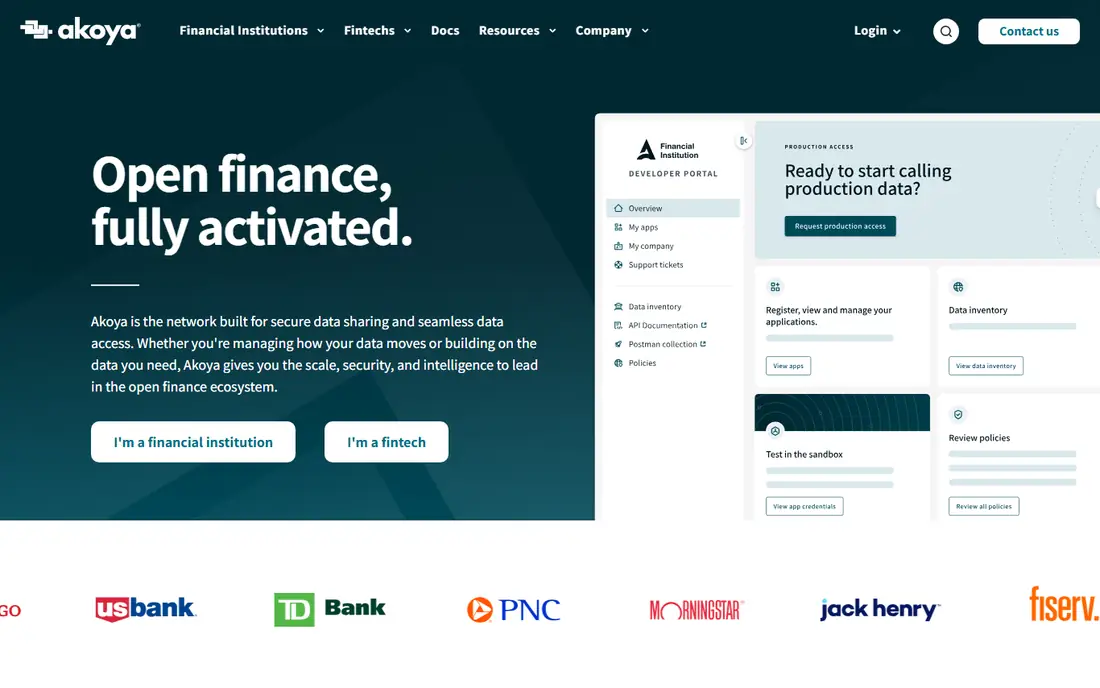
Akoya takes a different architectural position from every other provider here: access is API-only, with consumers granting permission through their bank and no credentials passing to the aggregator. That design answers the hardest security and compliance questions in one move, and it is why banks themselves participate in the network. For a product whose risk review will interrogate credential handling, Akoya removes an entire class of objection.
The practical limit is network coverage. Because Akoya depends on participating institutions, a team whose customers bank outside the network will need a fallback provider for those connections, which adds integration work. Pricing is agreed commercially, with a free sandbox for development. Shortlist Akoya when security architecture is the deciding factor, and map your top institutions against its network before committing.
What we like- No screen scraping and no credential sharing
- Permissioned consent model
- Strong security story
Watch out for- Network coverage depends on participating institutions
- May need a fallback provider
- Pricing not published
#5
Stripe Financial Connections
Best for: Stripe-based verification
Visit stripe.com
Starting priceSee website
Free planNo
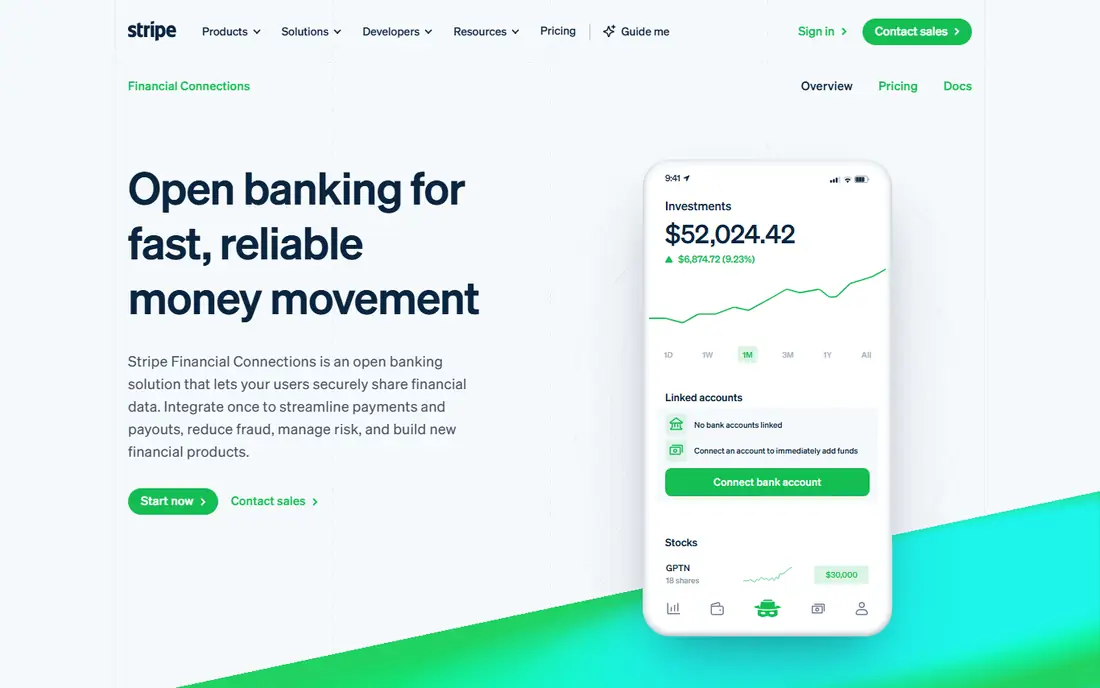
Stripe Financial Connections is the pragmatic choice for teams already running payments on Stripe. It verifies accounts and pulls balances for onboarding, payouts, and payment setup inside the same dashboard and API family as the rest of the Stripe stack, with per-call pricing that is easier to forecast than an enterprise contract. For a marketplace or platform that needs to verify a payout account, it is often the fastest path to production.
Scope is the limit. Financial Connections is a verification tool, not a full aggregation and enrichment platform, so products that need deep transaction history, categorization, or wealth data should pair it with another provider or choose a broader one. If Stripe is already your payments backbone, start here and add breadth only when the product demands it.
What we like- Native fit for Stripe payments and payouts
- Transparent usage pricing
- Strong uptime record
Watch out for- Narrower scope than full aggregators
- No broad enrichment suite
- Best value only inside Stripe
Starting priceSee website
Free planFree trial
Tink, owned by Visa, is the most complete European alternative on this list, combining account data, payment initiation, and lender products such as income and expense checks across thousands of European banks. A fintech serving several European markets can often cover data and payments under one integration, which simplifies both engineering and vendor management. Its underwriting products are genuinely useful for affordability checks.
The boundary is geographic. Tink's strength is Europe, and teams whose customers are mainly in the US or Latin America should look elsewhere. Pricing is usage-based and agreed commercially, with a sandbox for development. For a Europe-first product, Tink is the default shortlist entry, tested against TrueLayer on payment conversion and coverage for your specific markets.
What we like- Broad European bank coverage
- Data plus payments in one platform
- Income and risk products for lenders
Watch out for- Europe-centered
- US coverage is not the focus
- Pricing agreed commercially
Starting priceSee website
Free planFree trial
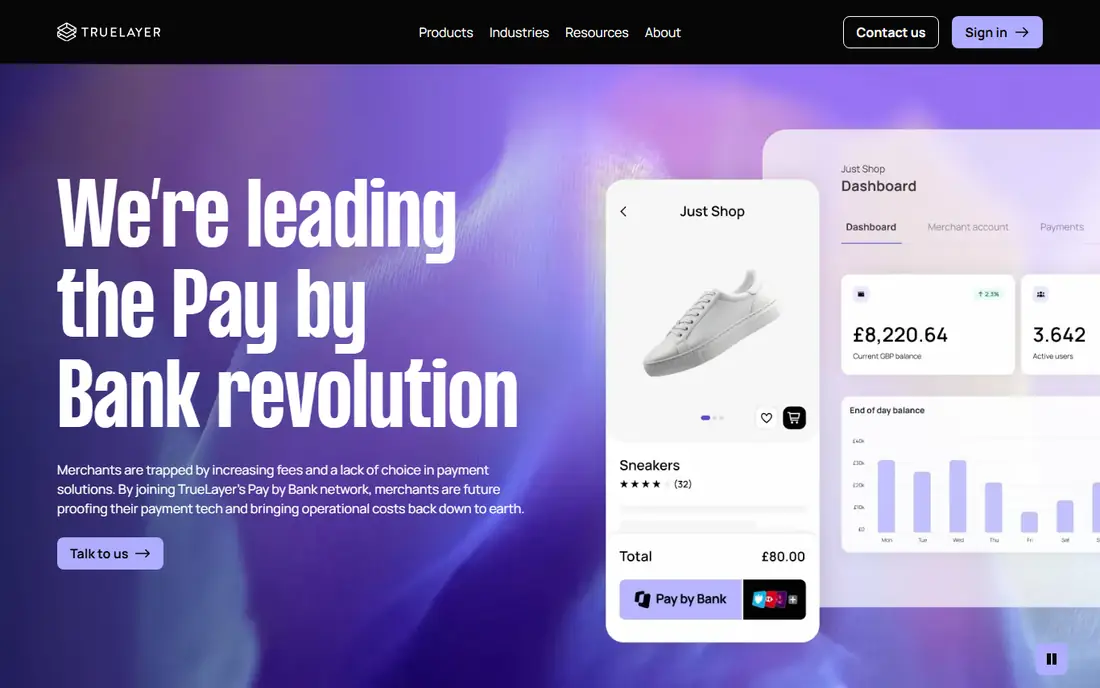
TrueLayer's pitch is that data and payments belong together. Its pay-by-bank product is used widely across UK open banking payments, and pairing it with account data and verification means a checkout or onboarding flow can confirm funds and move money in one journey. Variable recurring payments add subscription-style use cases that simple one-off payment APIs cannot serve.
Coverage is the constraint, as with Tink: TrueLayer is strongest in the UK and Europe, with Australia growing, and it is not a US aggregator. Pricing is transaction-based and varies by product, so model it against your expected payment volume rather than comparing headline rates. If your product monetizes through payments, TrueLayer's conversion record makes it the European pick to beat.
What we like- Strong pay-by-bank conversion
- Data plus verification beside payments
- Variable recurring payments support
Watch out for- Europe and Australia focus
- US coverage limited
- Pricing varies by product
Starting priceSee website
Free planFree trial
Salt Edge suits products that cross borders without wanting a vendor per region. Its aggregation reaches thousands of institutions across more than 50 countries, and it bundles the PSD2 compliance tooling that a company operating in Europe needs. For a personal finance or accounting product with users in several regions, one Salt Edge integration can replace a patchwork of local providers.
Depth is the honest caveat: coverage in a given market may be thinner than a regional specialist's, and payment features vary by country. Pricing is agreed commercially with a free trial for evaluation. Test Salt Edge against your top five markets specifically, and keep a regional specialist on the shortlist for any market where it falls short.
What we like- Coverage across 50+ countries
- PSD2 compliance tooling
- Data and payment APIs
Watch out for- Depth varies by market
- Smaller brand than Tink or TrueLayer
- Pricing not published
Starting priceSee website
Free planFree trial
Flinks is the Canada answer in a market where US providers often treat Canada as an afterthought. Its coverage of Canadian institutions and its detailed cash-flow and liability attributes make it a strong fit for lenders and fintechs serving Canadian customers, and it works as a North American complement to a US provider. Lenders that need liability detail for underwriting will find Flinks' attributes more useful than a generic feed.
Outside Canada, Flinks is not the right primary provider, so a global product should treat it as a regional specialist. Pricing is agreed commercially with a free trial. If your customer base is Canadian, or your lending product serves Canada alongside the US, Flinks belongs on the shortlist from day one.
What we like- Strong Canadian institution coverage
- Detailed cash-flow and liability attributes
- North American lender fit
Watch out for- Canada-centered
- Global coverage is limited
- Pricing not published
How we chose
We shortlisted providers that offer production financial-data APIs with permissioned consumer consent, excluding consumer budgeting apps and screen-scraping-only tools. Coverage was judged by region and by the institutions a real product would need, not by headline counts alone. Pricing figures come from each vendor's own pricing page or published comparison, checked in October 2026, and where pricing is agreed commercially we say so rather than inventing a number. We weighed consent architecture, verification and enrichment products, payment capability, developer experience, and support for the markets each vendor serves.
Testing coverage before you sign
Headline institution counts mislead. A provider can list thousands of banks and still connect poorly to the three your customers use most. Run the same set of real accounts through every shortlisted provider, measure reconnection rates over at least 30 days, and verify that consent revocation works cleanly. That test costs a few weeks and saves a migration later.
Consent and compliance are product features
Open banking regulation differs by region: PSD2 in Europe, FDX-aligned practices and evolving CFPB rules in the US, and local frameworks elsewhere. A provider's consent flow, data-retention policy, and audit trail are part of the product, not paperwork. Ask for them in writing during evaluation, and confirm how the provider handles a bank that changes its authentication flow.
This is not financial advice. These are developer infrastructure products, and the right choice depends on your product's markets, compliance obligations, and the institutions your customers use.
Frequently asked questions
What is the best Plaid alternative for US fintechs?
MX for data quality and enrichment, Finicity for lending verification, and Akoya when security architecture demands API-only access. Stripe Financial Connections is the simplest option for teams already on Stripe that mainly need account verification.
What is the best Plaid alternative in Europe?
Tink for the broadest data and payments platform, and TrueLayer when pay-by-bank payments are central to the product. Test both against your specific markets, since bank coverage and payment conversion vary by country.
Are Plaid alternatives cheaper than Plaid?
Pricing is mostly commercial and usage-based, so there is no universal answer. MX offers a free developer tier, Stripe publishes per-call pricing, and most others agree pricing through sales. Model total cost against your expected call volume and user count, not headline rates.
Do these providers store my customers' bank passwords?
It depends on the connection type. API-based providers like Akoya never receive credentials, since consumers authenticate at their bank. Other providers may use OAuth or, for some institutions, credential-based connections with encryption. Ask each vendor how each of your top institutions connects before you decide.
Can I use more than one open banking provider?
Yes, and many products do. A common pattern is a primary provider for the main market plus a regional specialist or a fallback for institutions the primary covers poorly. Budget for the extra integration and reconciliation work that a multi-provider setup creates.
Sources we checked (11)
- https://www.mx.com
- https://www.finicity.com
- https://www.yodlee.com
- https://akoya.com
- https://stripe.com/financial-connections
- https://www.tink.com
- https://truelayer.com
- https://www.saltedge.com
- https://www.flinks.com
- https://checkthat.ai/brands/plaid/alternatives
- https://dashdevs.com/blog/open-banking-providers/
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has 5+ years in B2B and SaaS SEO. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.
 Envestnet Yodlee
 Akoya
 Tink
 TrueLayer
 Salt Edge
 Flinks