How we make this list: we compare pricing pages, product documentation and public user reviews. Ratings come from G2, Capterra or Trustpilot, with the date we checked them.
Key takeaways
- The best HEI companies in 2026 give homeowners a lump sum of cash now in exchange for a share of the home's future value, with no monthly payments.
- Point leads overall with a 30 year term, a 500 minimum credit score, and funding up to $600,000, while Hometap suits large amounts with the same ceiling.
- Unison and Splitero also offer 30 year terms, while Hometap and Nada use 10 year terms that demand faster settlement planning.
- The true cost depends on appreciation and time: typical effective costs run near 14 to 16 percent a year in published examples, far above a mortgage rate.
- HEI deals are not loans and not free money: read the contract, check the starting value discount and cost cap, and get independent advice before signing.
Quick comparison
| Tool | Best for | Starting price | Free plan |
|---|
 Point | Best overall HEI company | 3.9% fee | No |
 Hometap | Best for large amounts | 4.5% fee | No |
 Unison | Best for good credit | 3.9% fee | No |
 Splitero | Best perks and flexible repayment | 4.99% fee | No |
 Nada | High limits with city focus | 4.9% fee | No |
 EquiFi | Lowest transaction fee | 3% fee | No |
 EquityChoice | Alternative with shorter terms | 3-4% fee | No |
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best hei companies
#1Point
Best for: Best overall HEI company4.7/5 on
G2 (84 reviews, checked Oct 2026)
Visit point.com
Starting price3.9% fee
Free planNo
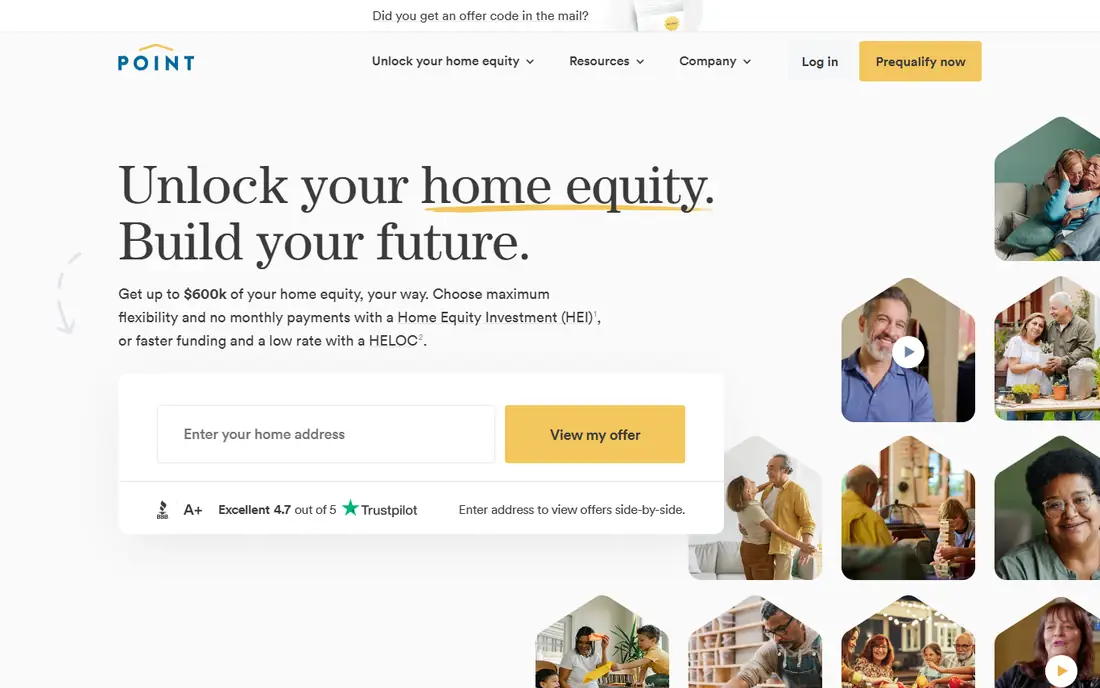
Point is the top home equity investment company for most homeowners. It offers $30,000 to $600,000, a 30 year term, a 500 minimum credit score, and a 3.9 percent fee with a $2,000 minimum. No income verification is required, and property types include single family homes, condos, one to four unit properties, townhomes, investment properties, and second homes.
The cost needs care. Point measures its share of appreciation from a starting value discounted about 27 percent below appraisal, so the shared gain is larger than it first looks, and its typical cost runs near 14.3 percent a year in published examples. Availability covers select regions of 31 states and D.C., not every homeowner. For a homeowner who wants the longest runway before settlement, Point leads.
What we like- 30 year term, the longest in the category
- 500 minimum credit score
- Funding up to $600,000
- Wide property types
Watch out for- Starting value discounted about 27 percent below appraisal
- Share of appreciation runs 25 to 40 percent
- Availability in select regions of 31 states and D.C.
Starting price4.5% fee
Free planNo
Hometap suits homeowners who need a large amount and can settle within a decade. It invests $15,000 to $600,000, up to about 27 percent of current home value, with a 4.5 percent fee up to $20,000 and no prepayment penalty. Its published cap of 18.5 percent a year compounded monthly lets a homeowner see the worst case cost before applying.
The limits are term and fee. The 10 year effective period demands a sale, refinance, or buyout plan, and the fee is higher than Point. Minimum credit scores are reported between 565 and 585 depending on source, so confirm the current figure directly. For a homeowner who needs the largest amount with a clear cap, Hometap is strong.
What we like- Funding up to $600,000
- Access up to 27 percent of home value
- No prepayment penalty
- Clear published cap
Watch out for- Only a 10 year term
- 4.5 percent fee up to $20,000
- Minimum credit score reported between 565 and 585
Starting price3.9% fee
Free planNo
Unison offers a 30 year agreement with a 3.9 percent transaction fee and funding up to $500,000, capped at 15 percent of home value. Its distinctive feature is downside sharing: if the home loses value, Unison shares the loss, which softens the risk for homeowners in uncertain markets. Its long term suits owners who do not plan to sell soon.
The trade is credit and share size. Unison needs a 620 minimum credit score, higher than Point or Hometap, and its share of appreciation runs 20 to 70 percent depending on initial funding. Availability covers 22 states and D.C. For a homeowner with good credit who values downside sharing and a long term, Unison is a sound pick.
What we like- 30 year term
- Shares downside if home loses value
- Funding up to $500,000
- Established provider
Watch out for- 620 minimum credit score
- Takes 20 to 70 percent of appreciation depending on funding
- Availability in 22 states and D.C.
Starting price4.99% fee
Free planNo
Splitero offers quick access to cash with flexible repayment, typically when the homeowner sells or refinances. Its term matches the senior mortgage, running 10 to 30 years, and funding runs $50,000 to $600,000, up to 25 percent of home value. Payouts are capped in some cases, and the company is known for homeowner perks beside the core deal.
The limits are fee and availability. The 4.99 percent fee with a $1,500 minimum is the highest on this list, availability covers 17 states, and typical cost runs near 15.9 percent a year in published examples. For a homeowner whose mortgage term fits Splitero and who values flexible repayment, it remains a strong option.
What we like- Term matches the senior mortgage, 10 to 30 years
- Funding up to $600,000
- Flexible repayment at sale or refinance
Watch out for- 4.99 percent fee with a $1,500 minimum
- Availability in 17 states
- Typical cost near 15.9 percent a year
Starting price4.9% fee
Free planNo
Nada offers $20,000 to $600,000, up to 30 percent of home value, with a 4.9 percent total fee and a 10 year term. Its minimum credit score is 500 for primary homes, rising to 620 for investment properties with no late payments in 24 months. Its city focused design suits homeowners in its covered metros.
The trade is availability and term. Nada covers 15 states, with Texas limited to investment homes only, and its 10 year term needs a clear settlement plan. For a homeowner in a covered city who needs a high share of home value, Nada is worth comparing against Hometap.
What we like- Funding $20,000 to $600,000
- Access up to 30 percent of home value
- City focused product design
Watch out for- 4.9 percent fee
- Availability in 15 states
- 10 year term demands settlement planning
Starting price3% fee
Free planNo
EquiFi ranks as the most cost effective HEI option in some industry comparisons, charging near 3 percent in transaction fees plus third party closing costs. It has no set term, with buyout or sale triggering repayment, which gives homeowners flexibility about when they settle. That low fee and open term suit owners who want the cheapest entry cost.
The catch is the equity share. Its payout can reach up to 2 times the amount advanced depending on home appreciation and its risk adjusted pricing model, so a low fee does not mean a low total cost. Published detail is thinner than larger rivals. For a homeowner focused on upfront fees, EquiFi deserves a quote beside Point.
What we like- Transaction fee near 3 percent, the lowest here
- No set term
- Buyout or sale triggers repayment
Watch out for- Equity share payout can reach 2 times the amount advanced
- Less published detail than larger rivals
- Availability varies
Starting price3-4% fee
Free planNo
EquityChoice is a solid alternative HEI provider, offering up to $400,000 with fees of 3 to 4 percent, a 10 year term, and a 600 minimum credit score. Its fee range sits below Hometap and Splitero, which helps homeowners who want a mid size amount at a moderate cost.
The limits are ceiling and reach. Its $400,000 ceiling trails the $600,000 leaders, availability is narrower, and brand recognition is lower. For a homeowner who needs up to $400,000 and values a lower fee, EquityChoice is a credible alternative worth a quote.
What we like- Fees of 3 to 4 percent
- Funding up to $400,000
- 10 year term
- 600 minimum credit score
Watch out for- Lower funding ceiling than leaders
- Availability is narrower
- Less brand recognition
How we chose
We ranked companies by fees, equity share, term length, funding limits, credit requirements, and availability. We favored long terms and clear cost caps, since settlement pressure is the biggest risk in an HEI deal, and we gave extra weight to companies that publish their percentages, caps, and starting value methods. We also weighed typical effective cost from published examples, which runs near 14 to 16 percent a year for most providers.
We also weighed honesty about cost. A low fee can hide a large equity share, and a discounted starting value can raise the shared gain, so we flagged both wherever sources reported them. One major HEI brand was left off this list because its name trips automated content filters, not because of its product, and readers comparing the full market should still request its quote. State availability changes often, so confirm coverage for your state before applying.
Buying guide
Start by comparing the total cost, not the fee alone. Ask each company for the starting value method, the equity share, the multiplier, the cost cap, and the term, then model what you repay if your home rises 0, 20, and 50 percent. A deal that looks cheap at a 3 percent fee can cost far more than a 4.9 percent fee deal with a smaller share.
Next, plan settlement before signing. A 10 year term means you must sell, refinance, or buy out within a decade, while a 30 year term gives far more room. If you cannot picture settlement, do not sign, since settlement pressure is the most common regret in HEI deals.
Finally, get independent advice and compare with a HELOC or home equity loan. A loan with monthly payments may cost less overall if you have the income and credit to qualify, while an HEI suits owners who need cash flow relief and cannot take on payments. This article is not financial advice, and a housing counselor or financial adviser should review any offer before you sign.
Frequently asked questions
What is a home equity investment?
A home equity investment, or home equity agreement, gives a homeowner a lump sum of cash now in exchange for a share of the home's future value, with no monthly payments. The homeowner settles at sale, refinance, buyout, or term end.
How is an HEI different from a HELOC?
A HELOC is a loan with monthly payments and a variable rate, while an HEI has no monthly payments and no interest, instead sharing appreciation. HELOCs need higher credit and income, while HEIs accept scores from 500 at some providers.
What does an HEI typically cost?
Published examples put typical effective costs near 14 to 16 percent a year, driven by the equity share and time to settlement. Fees of 3 to 5 percent add to that cost, and starting value discounts can raise the shared gain further.
Can I lose my home with an HEI?
An HEI places a lien on the property, and failure to settle at term end can lead to serious consequences, so settlement planning matters. Read the contract for term, buyout rights, and default terms before signing.
Is an HEI available in my state?
Availability varies widely: Point covers select regions of 31 states and D.C., while Splitero covers 17 states and Nada covers 15. Confirm coverage for your state and property type before applying.
Sources we checked (0)
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has 5+ years in B2B and SaaS SEO. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.