How we make this list: we compare pricing pages, product documentation and public user reviews. Rankite is independent; if a vendor ever pays for a featured spot, that listing is clearly labeled Partner.
Key takeaways
- Self and CreditStrong use credit-builder loans: structured payments reported to the bureaus that build history over time.
- Kikoff and Kovo are the low-cost entry points, reporting small monthly payments to all three major bureaus.
- Chime and Current bundle credit building into banking: no fees, no interest, tied to your spending.
- Grow Credit builds history from subscriptions you already pay for, like streaming services.
- Experian Boost is free and instant, but only affects your Experian report.
Quick comparison
| Tool | Best for | Starting price | Free plan |
|---|
 Self | Credit-builder loans | See website | No |
 Kikoff | Low-cost starter | See website | No |
 MoneyLion | Credit building plus banking | See website | No |
 Chime | Fee-free credit building | Free | Yes |
 Grow Credit | Building from subscriptions | See website | Yes |
 Kovo | Affordable four-bureau reporting | See website | No |
 CreditStrong | Larger installment tradelines | See website | No |
 Experian Boost | Free Experian boost | Free | Yes |
 Current | Banking with credit building | Free | Yes |
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.
The best credit builder apps
Starting priceSee website
Free planNo
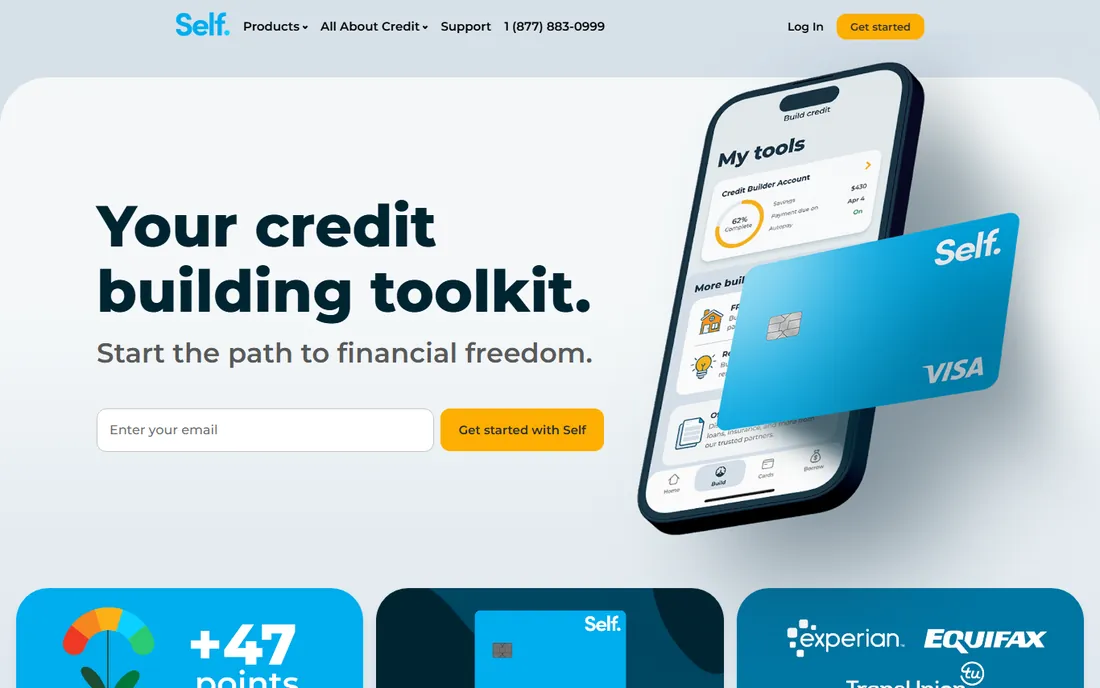
Self's credit-builder loan works like a forced savings plan in reverse. You choose a plan, make monthly payments, and Self reports each on-time payment to Experian, Equifax, and TransUnion. At the end of the term, you get the money back minus fees and interest. It builds the payment history that matters most in credit scoring, plus a mix of account types.
The commitment is real: you pay every month for the length of the plan, and missing payments hurts rather than helps. This is a slow, steady tool, not a quick fix. For people starting from zero or rebuilding, Self's structured approach and bureau coverage make it one of the most established options.
What we like- Structured plans for different budgets
- Reports to all three bureaus
- Optional secured card
Watch out for- Monthly payments required
- No instant results
Starting priceSee website
Free planNo
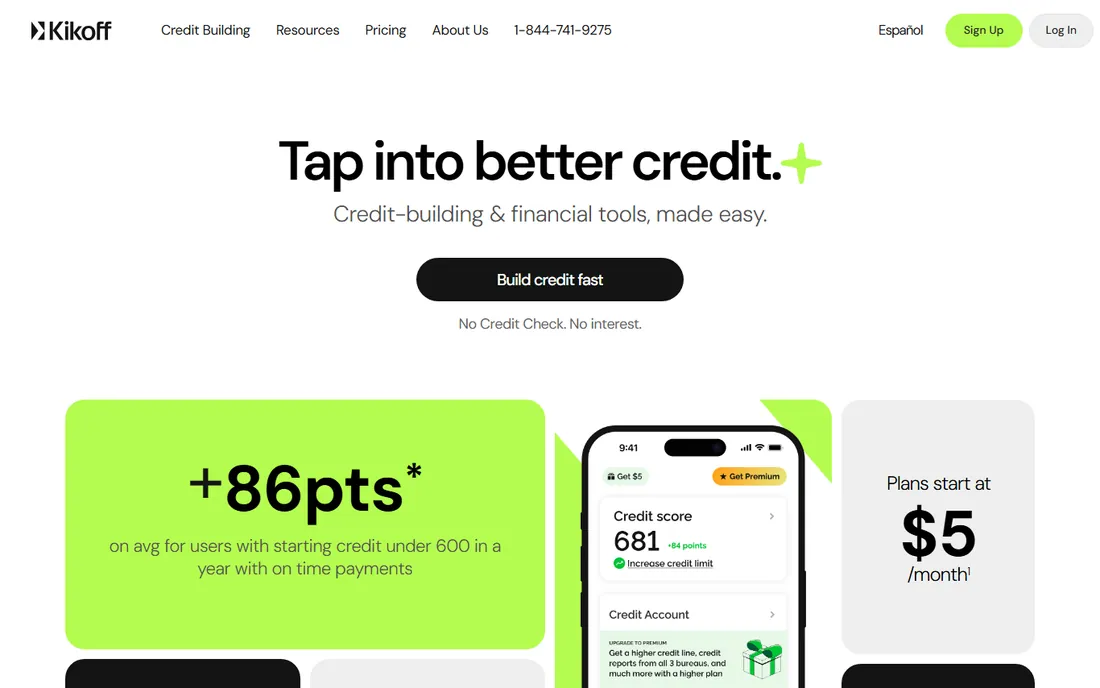
Kikoff keeps it simple and cheap: a small line of credit whose monthly payments get reported to all three major bureaus. There is no hard credit check to start, approval is fast, and the cost is among the lowest in the category. For someone who just needs positive payment history appearing on their reports, Kikoff does exactly that.
The credit amounts are small by design; this builds history, not buying power. Features beyond the core reporting are thin. But as a first step, especially for young adults or newcomers to the US credit system, Kikoff's low cost and simplicity are hard to beat.
What we like- Very affordable
- Reports to all three bureaus
- Simple to start
Watch out for- Small credit lines
- Limited features beyond building
Starting priceSee website
Free planNo
MoneyLion bundles credit building into a broader financial app: banking, investing, cash advances, and budgeting alongside the credit-builder loan. The loan payments report to the bureaus like Self's, while the surrounding tools aim to improve your overall financial picture. It suits people who want one app for several money jobs.
The membership fee adds up, and the app's many features can feel scattered. If you only want credit building, simpler tools cost less. But for users who will actually use the banking and budgeting features, MoneyLion's bundle logic works. Check the current membership terms carefully before committing.
What we like- Combines banking, investing, and credit building
- Cash advances
- Financial tools
Watch out for- Membership fee
- Feature sprawl can confuse
Starting priceFree
Free planYes
Chime's Credit Builder card works differently: it is a secured card with no fees, no interest, and no credit check, where your spending limit is what you deposit. Use it for everyday purchases, and Chime reports your activity to the bureaus. There is no monthly fee and no APR because you cannot carry a balance in the traditional sense.
The catch is the ecosystem: you need a Chime checking account with qualifying direct deposits to use it fully. It builds history based on your actual spending rather than a separate loan payment. For people already banking with Chime, it is the simplest credit-building on-ramp available.
What we like- No fees, no interest, no credit check
- Tied to everyday spending
- Simple
Watch out for- Requires Chime banking
- Only helps with Chime activity
Starting priceSee website
Free planYes
Grow Credit's insight is that you already pay bills every month: streaming, phone, and other subscriptions. Its service reports those payments to the bureaus, turning existing spending into credit history. The free tier covers basic subscriptions, with paid tiers adding more services and higher limits.
Each reported account is small, so the impact builds gradually rather than dramatically. It works best combined with another builder (like Self or Kikoff) rather than alone. But for someone who wants to start building credit without changing their spending at all, Grow Credit's free tier is genuinely useful.
What we like- Builds credit from existing subscriptions
- Free tier
- No hard inquiry
Watch out for- Small impact per account
- Higher tiers cost monthly
Starting priceSee website
Free planNo
Kovo stands out by reporting to four bureaus (Experian, Equifax, TransUnion, plus Innovis) rather than the usual three. The monthly subscription covers the credit account plus extras like identity monitoring. For thorough coverage of your credit file, the fourth bureau is a real differentiator.
As a newer company, Kovo has a shorter track record than Self or Kikoff. The subscription is affordable but ongoing. For people who want maximum bureau coverage at a low monthly cost, Kovo's four-bureau reporting is unique in this price range.
What we like- Reports to four bureaus including Innovis
- Affordable
- ID monitoring included
Watch out for- Newer company
- Monthly subscription
Starting priceSee website
Free planNo
CreditStrong targets people who want bigger tradelines on their reports. Its credit-builder accounts come in larger amounts than most competitors, which can improve your credit mix (installment plus revolving looks better than either alone). Payments report to all three bureaus, and the structure includes a savings component.
Larger accounts mean larger monthly payments and longer terms, so the commitment is serious. This is not a starter tool; it suits people with some history who want to strengthen their profile. For that audience, CreditStrong's installment tradelines fill a gap the small-dollar builders leave.
What we like- Larger loan amounts build credit mix
- Savings component
- All three bureaus
Watch out for- Higher monthly payments
- Longer commitments
Starting priceFree
Free planYes
Experian Boost is the rare free lunch in credit: connect your bank accounts, let Experian count your utility, phone, and streaming payments, and see your Experian score update. It takes minutes, costs nothing, and cannot hurt you. Everyone with thin credit should do this first.
The limitation is scope: it only affects your Experian report and score, not Equifax or TransUnion. The score lift is usually modest. Think of Boost as a free first step, not a strategy. Pair it with a real builder from this list for meaningful progress.
What we like- Completely free
- Instant results
- No risk
Watch out for- Only affects Experian
- Small score impact for most
Starting priceFree
Free planYes
Current is a mobile bank with credit building woven in: no monthly fees, early direct deposit, budgeting tools, and features that report your banking activity to help build credit. Like Chime, it suits people who want banking and credit progress in one app without fees.
The credit-building impact is gradual and tied to your banking activity rather than a dedicated tradeline. It will not replace a credit-builder loan for serious rebuilding. But as a free, fee-free banking relationship that nudges your credit upward, Current is a solid choice.
What we like- No monthly fees
- Early direct deposit
- Credit building built in
Watch out for- Banking features vary
- Credit impact is gradual
How credit builder apps actually work
Every app here exploits the same mechanics of credit scoring. Payment history is the biggest factor, so all of them create a recurring payment that gets reported to the bureaus each month. Credit-builder loans (Self, MoneyLion, CreditStrong) do this with an installment account; subscription reporters (Kikoff, Kovo, Grow Credit) do it with small revolving or subscription accounts; banking apps (Chime, Current) report your spending activity; Experian Boost adds utility payments to one bureau. None of them erase bad history; they add good history alongside it. That is why they work slowly and why consistency matters more than which app you pick. The honest timeline: expect meaningful movement in six to twelve months of on-time payments, not six days.
What to check before you commit
Which bureaus get the reports
All three major bureaus (Experian, Equifax, TransUnion) is the standard you should demand. Kovo adds Innovis for four. Experian Boost only touches Experian. If an app reports to just one bureau, your effort helps only a third of your credit picture.
Total cost over the full term
Monthly fees look small until multiplied by 12 or 24 months. Add up the entire commitment: payments, fees, and interest. Compare that total against the alternatives, including secured credit cards from major banks, which sometimes cost less overall. The cheapest monthly price is not always the cheapest total.
What happens if you miss a payment
This is the critical question. A missed payment on a credit-builder product can hurt your score, the opposite of the goal. Understand the grace periods, late fees, and reporting rules before signing up. If your income is irregular, prefer products with flexibility over rigid loan schedules.
Your starting point matters
No credit history, thin history, and damaged history need different tools. True beginners do well with Kikoff, Chime, or Grow Credit. Rebuilders with damaged credit need the structured history of Self or CreditStrong, and should address negative items separately. There is no app that removes collections or late payments; beware anyone claiming otherwise.
How we chose
We selected credit-building apps available to US consumers in 2026, covering credit-builder loans, subscription reporting, banking-based building, and free boost tools. We evaluated each on bureau coverage, cost transparency, company reputation, and fit for different starting points. We excluded apps making unrealistic promises and general credit monitoring tools that do not build history. No company paid for placement. This guide is educational, not financial advice; consider speaking with a nonprofit credit counselor for personalized guidance.
Frequently asked questions
Do credit builder apps actually work?
Yes, with realistic expectations. They add positive payment history to your credit reports, which is the largest factor in credit scores. They do not remove negative items or produce overnight changes. Most users see meaningful improvement after six to twelve months of consistent on-time payments.
Will a credit builder app hurt my credit score?
It can, in two ways: the initial account opening may cause a small temporary dip, and missed payments will definitely hurt. Made consistently, payments help. The apps themselves are neutral tools; the outcome depends on your payment behavior.
Which credit bureaus do these apps report to?
Most report to all three major bureaus: Experian, Equifax, and TransUnion. Kovo also reports to Innovis. Experian Boost only affects Experian. Always confirm current bureau coverage on the provider's site before signing up, as reporting relationships can change.
How long does it take to build credit with these apps?
Expect the first reported payments within one to two months, and meaningful score movement within six to twelve months of on-time payments. Building excellent credit takes years regardless of method. Anyone promising dramatic results in weeks is not being honest.
Are credit builder apps better than secured credit cards?
They serve different purposes and work well together. Secured cards build revolving history and are widely accepted by lenders; builder apps create structured installment history. Many advisors recommend both: a secured card for daily use plus a builder loan for payment history diversity. Neither is universally better.
Sources we checked (11)
- https://www.self.inc
- https://kikoff.com
- https://www.moneylion.com
- https://www.chime.com
- https://growcredit.com
- https://www.kovocredit.com
- https://www.creditstrong.com
- https://www.experian.com
- https://current.com
- https://wallethub.com/best-credit-builder-apps
- https://thecollegeinvestor.com/38589/best-credit-building-apps/
Is your product missing or out of date?
We review this list regularly. Vendors can request a listing, send updated pricing or ask about featured placement.

Shihab Mia · Founder, Rankite
Shihab has spent more than a decade helping SaaS and e-commerce brands grow through search. He writes Rankite's software buying guides from pricing pages, documentation and public user reviews. More about Shihab.